Finding investment options in India is not difficult, but choosing where the money should go is difficult.
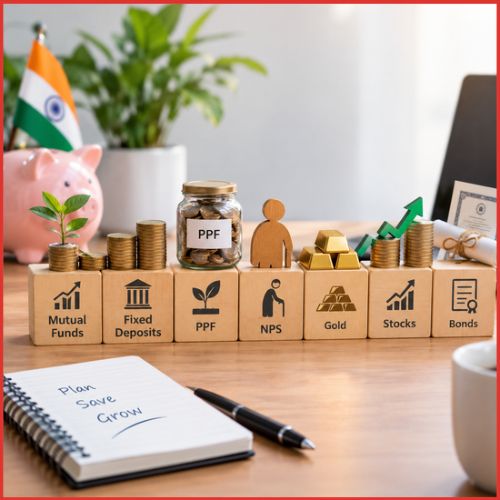
A fixed deposit offers stability. Equity mutual funds offer long-term growth potential but come with market risk.
PPF provides a government-backed savings route. Gold can add diversification whereas NPS focuses on retirement.
Each option solves a different problem.
There is no single investment that offers high returns, complete safety and easy access to money at the same time. The choice depends on the financial goal, time horizon, risk tolerance, liquidity requirement and tax treatment.
SEBI also advises investors to consider these factors before selecting an investment product.
So the question is: Where should the money go, and why?
How to Choose the Right Investment Option in India
An investment decision can start with five questions.
| Factor | Question |
| Financial goal | What is the money being saved for? |
| Time horizon | When will the money be needed? |
| Risk | How much loss or fluctuation can be tolerated? |
| Liquidity | How quickly might the money need to be accessed? |
| Tax | How will the final return be taxed? |
Time changes the decision.
Money required next year cannot be invested in the same way as money being accumulated for retirement 20 years from now. SEBI advises investors to match the investment with the time horizon and risk tolerance, particularly warning against using volatile investments for short-term needs.
A higher expected return usually comes with greater uncertainty. An investor who cannot tolerate a temporary fall in value may choose differently from someone investing money that can remain untouched for many years.
The purpose should come first. The product comes after it.
Best Investment Options in India for Beginners
For a beginner, the first investment decision may not actually be an investment.
It may be building financial stability.
SEBI advises investors to maintain an emergency fund, have a stable source of income and consider insurance protection before building a long-term investment strategy.
1. Build Emergency Savings First
Money required for rent, medical expenses, education fees or other immediate needs should remain accessible.
A market-linked investment is a poor emergency reserve if a market fall can force a sale at the wrong time.
The exact emergency fund for you can be different depending on your income and household situation.
The basic principle remains the same: short-term money needs short-term access.
2. Understand Risk Before Chasing Returns
A return figure alone tells very little about the investment.
A product that produced a strong return in the past can still fall sharply in the future. SEBI specifically warns that past performance does not guarantee future returns.
It recommends understanding an investment’s risks before investing.
3. Start With Simple Products
Beginners do not need a complicated portfolio containing several asset classes, multiple schemes and individual stocks from the first month.
SEBI recommends that new investors should learn the basics and start with simpler investment options before moving towards complex products such as derivatives.
Understanding one investment is more useful than owning five that cannot be explained.
4. Check Charges and Taxation
The return shown on a flashy investment advertisement may not represent the amount finally retained by the investor.
Charges, brokerage, expense ratios, taxes, exit conditions and other costs can affect the outcome.
SEBI also advises investors to carefully note applicable fees and charges and read investment documents before investing money.
5. Avoid Investing Money That Is Needed Soon
This is where many beginners make mistakes.
An investment can be fundamentally sound and still not good for money required within months.
The investment horizon must match the product.
6. Do Not Confuse Diversification With Owning Everything
Diversification can reduce concentration risk. Owning too many similar products does not automatically create a better portfolio.
A beginner with limited capital may need only a few understandable investments rather than a collection of overlapping schemes.
Best Investment Options in India
Once the financial foundation is in place, the investment options become easier to compare.
Mutual Funds and Index Funds
Mutual funds have become one of India’s most visible investment routes, particularly through SIPs.
An equity mutual fund invests across a portfolio of shares, while an index fund tracks a market index.
The investor gets diversification without having to select every company individually. The trade-off is market risk.
One needs to understand that SIP is not an asset class. It is a method of investing a fixed amount periodically into a mutual fund scheme.
AMFI reported SIP contributions of ₹32,297 crore in August 2026, with more than 10.75 crore outstanding SIP accounts and SIP assets of about ₹18.62 lakh crore.
The scale explains the growing visibility of SIP investing but it does not make every mutual fund suitable for every investor.
Equity mutual funds generally make more sense for goals with longer horizons, where temporary market declines can be absorbed without disrupting the financial goal.
Fixed Deposits
Fixed deposits are useful for investors who value stability and predictable interest.
The structure is straightforward: a specific amount is deposited for a chosen tenure at a specified rate, subject to the bank’s terms.
FDs can therefore fit short- and medium-term financial goals where large market fluctuations are undesirable.
The advertised interest rate is only one part of the calculation. Tax and inflation also affect the real outcome.
Public Provident Fund
PPF is designed for disciplined long-term saving.
Its long duration and withdrawal restrictions make it fundamentally different from a normal savings account or a short-term FD.
It can be a good choice for investors who want a government-backed savings route and do not need immediate access to the money.
PPF rates are notified by the government and can change across periods. The Department of Economic Affairs publishes the relevant small savings notifications. So the applicable rate should be checked against the current official notification.
National Pension System
NPS is designed around retirement accumulation and it should be evaluated considering that only.
The product has a retirement-focused structure, investment choices across asset classes and specific withdrawal rules. Therefore, it belongs more naturally in a long-term retirement plan than in money meant for an immediate goal.
Tax treatment and withdrawal conditions also need to be understood before investing.
Bonds and Government Securities
Bonds represent lending rather than ownership.
The investor lends money to an issuer and receives interest according to the security’s terms, with repayment subject to the instrument and issuer.
Government securities and corporate bonds can have different levels of risk.
Credit risk, interest rate risk and liquidity can affect the outcome. SEBI advises investors to understand the specific risks attached to securities rather than treating the broad category as risk free.
Gold
Gold plays a different role in a portfolio. It can provide diversity and exposure to a physical commodity rather than a company or a debt issuer.
Gold can be held through several routes, including physical gold and market-based products. But it is not automatically a substitute for growth assets.
The appropriate role depends on the wider portfolio and financial objective.
Direct Stocks
Direct stocks provide direct exposure to individual companies.
The potential return can be high. So can the loss. It is very volatile in nature.
Individual stock investing requires analysis of the company’s financial position, valuation, business model, industry conditions and future prospects.
The investor also carries company-specific risk that a diversified fund may spread across many businesses.
Direct stocks therefore demand more involvement than a broad index fund or diversified mutual fund.
REITs
REITs provide a way to gain exposure to income-generating real estate without buying an entire commercial property.
They can add another type of asset to a portfolio.
Their prices still depend on market conditions, and the underlying properties face their own business and economic risks.
REITs are therefore better understood as one possible allocation rather than a universal replacement for property, equity or debt.
Best Investment Options Based on Time Horizon
The same investment can have a different level of suitability depending on when the money is required.
| Time Horizon | Investment Types That May Be Considered |
| Less than 1 year | Savings, suitable FDs and other lower-volatility options |
| 1 to 3 years | FDs and selected lower-risk debt options |
| 3 to 5 years | A mix of debt and growth assets depending on risk |
| 5 to 10 years | Equity mutual funds, index funds and diversified portfolios may become relevant |
| 10+ years | Equity-oriented investments, retirement products and diversified portfolios |
These are broad categories rather than fixed rules.
SEBI’s guidance is clear on the underlying principle: short-term money should not normally be exposed to unsuitable levels of volatility, while long-term investors can consider assets with greater growth potential.
Where Should Someone Invest ₹10,000 Per Month?
A ₹10,000 monthly investment does not automatically require a complicated allocation.
The goal determines the route.
For a long-term wealth creation objective, diversified equity mutual funds or index funds may be considered by investors who can tolerate market fluctuations.
For a short-term purchase, stability and access to money may matter more.
For retirement, NPS can be considered alongside other long-term investments depending on the investor’s objectives and tax position.
The same ₹10,000 can therefore produce very different investment decisions.
Where Should Someone Invest ₹1 Lakh?
A ₹1 lakh lump sum needs one question before every other question:
When will the money be needed?
If it is part of an emergency reserve, it belongs somewhere accessible.
If it is needed for a purchase within a year, exposing the entire amount to equity market volatility may create an avoidable problem.
If it can remain invested for many years, diversified market-linked investments may become more relevant for an investor with the appropriate risk capacity.
A lump sum does not need to be divided across every available investment product.
Common Investment Mistakes to Avoid
- Chasing recent returns — past performance can provide information, but it cannot guarantee future returns.
- Ignoring inflation — a 7% nominal return does not necessarily mean 7% real growth in purchasing power.
- Investing without liquidity — a profitable investment can still become a poor decision if money has to be withdrawn at an inconvenient time.
- Buying too many products — five funds holding similar companies may provide less meaningful diversification than their number suggests.
- Ignoring charges and taxes — the headline return is not the final return.
- Following trends without understanding them — SIP, gold ETFs, international stocks or a popular mutual fund may attract attention without automatically matching an investor’s financial goal.
What Is Trending in Indian Investing in 2026?
The mutual fund and SIP segment remains one of the clearest current investment trends.
AMFI data shows SIP contributions reached ₹32,297 crore in August 2026, while contributing SIP accounts stood at more than 10 crore.
International investing is another emerging search trend.
Financial Express reported on September 25, 2026 that Google Trends searches related to investing in global markets had risen more than 5,000% over the previous 12 months.
The report also cited RBI data showing nearly $2.6 billion sent abroad by Indians for investments during FY2025 to FY2026.
The increase in interest does not remove the need for due diligence.
International assets introduce currency and regulatory considerations in addition to ordinary investment risks.
Frequently Asked Questions
Which is the best investment option in India?
There is no single investment that fits every investor. The appropriate choice depends on the goal, time horizon, risk tolerance, liquidity requirement and tax position.
Which investment is best for beginners in India?
Beginners generally benefit from building emergency savings first, understanding risk and starting with simple products that can be understood clearly. SEBI specifically recommends learning the basics before moving towards more complex investments.
Is SIP better than an FD?
SIP and FD serve different purposes. A SIP into an equity mutual fund carries market risk and can suit long-term growth objectives, while an FD can suit investors who prioritise stability and predictable interest.
Is PPF suitable for long-term investment?
PPF can suit investors looking for a government-backed long-term savings product and who can accept limited liquidity.
Is gold a good investment in India?
Gold can provide diversification and exposure to a different asset type. Its role depends on the investor’s wider portfolio and objective.
Where should a beginner invest ₹10,000 per month?
The answer depends on the goal and time horizon. A long-term investor may consider diversified market-linked investments, while someone saving for a near-term goal may place greater importance on stability and liquidity.
Where should someone invest ₹1 lakh?
The decision depends mainly on when the money will be required, whether emergency savings are already in place and how much investment risk can be tolerated.
Final Takeaway
The best investment option is not the one showing the highest return in recent times. It is the one that fits your needs.
Short-term money needs liquidity while long-term wealth building can accommodate more market risk. A retirement plan needs a different structure.
Diversification can reduce dependence on a single asset class.
A useful framework is simple:
Goal → time horizon → risk → liquidity → tax → investment option
This approach turns into a long list of financial products and helps make clearer decisions.
It is true that India’s investment market is changing quickly, but the basic principle remains steady.
Remember “The purpose comes first. The product comes after it”.