Ask ten Indian families where they park their savings and you will get ten different answers. One swears by the gold coin bought every Dhanteras. Another has had a SIP running since 2019. A cousin trades on his phone during lunch and never stops talking about it.
If you are stuck somewhere in the middle of that argument, the question of gold vs mutual funds vs stocks 2026 is probably on your mind. Equity markets have had their swings, gold prices have had a strong run, and everyone around you has an opinion. This guide looks at how gold investment 2026 stacks up against mutual funds and direct equities, so you can match the choice to your own goals rather than to the loudest voice in the room.
One caution before we begin. Returns, prices and tax rules change over time. Treat what follows as a way of thinking, not a forecast, and check current figures before you put money down.
Why the Gold vs Stocks Debate Never Goes Away
Indians have a long relationship with gold. It is jewellery, a wedding gift, an emergency reserve and a mark of status, all in one. Shares arrived in most households much later, first through direct holdings and then, over the last decade, through mutual funds and monthly SIPs. Today all three sit side by side in almost every conversation about the best investment options 2026.
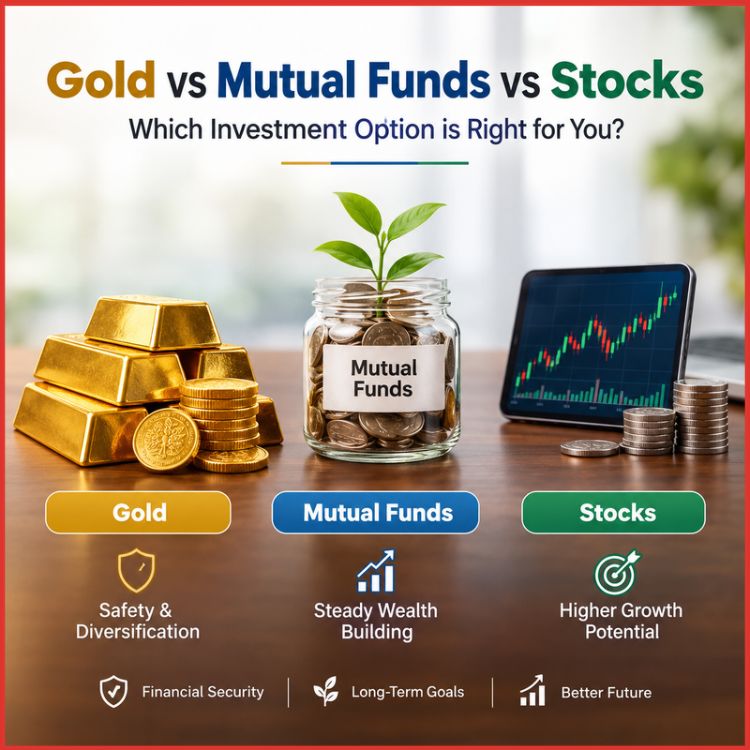
What has changed is access. You no longer need a jeweller or a broker’s office. A gold ETF, a mutual fund and a share can all be bought from the same app in a few minutes. Easy access, though, does not make the options interchangeable. Gold protects, mutual funds build steadily, and stocks reward people who do their homework. Most costly mistakes begin when one is asked to do the job of another.
Gold Investment 2026: Safety Net or Growth Engine?
Gold’s biggest strength is that it tends to hold its ground when other assets wobble. When equity markets turn nervous or the rupee weakens against the dollar, gold has often stepped up. That is why many planners treat gold investment 2026 as portfolio insurance rather than a wealth-creation tool.
The weakness is just as clear. Gold pays no dividend and no interest. Your gain depends entirely on the price, and long flat stretches are normal. Anyone who bought near a peak may have waited years just to break even.
The main ways to own gold
- Physical gold: Jewellery, coins and bars carry emotional value, but making charges, purity checks, storage and resale deductions eat into the return.
- Gold ETFs and gold mutual funds: These track gold prices with no storage worries and let you start small. ETFs need a demat account; gold funds usually do not.
- Sovereign Gold Bonds: They paid interest on top of price gains, but fresh issues have been scarce lately, so check current availability, including the secondary market.
- Digital gold: Convenient, but it sits outside the regulatory framework that covers ETFs and mutual funds, so read the provider’s terms carefully.
For anyone who wants gold as a financial asset rather than as jewellery, the ETF or fund route is usually cleaner and cheaper.
Mutual Fund Investment India: The Steady Middle Path
For people who want equity exposure without picking companies, mutual fund investment India offers a practical route. A fund pools money from many investors, and a manager or an index decides what to buy. You get diversification from the very first instalment.
The real advantage is discipline. A monthly SIP takes emotion out of timing. When markets fall, the same amount buys more units; when they rise, it buys fewer. Over long periods, this habit suits salaried people who cannot watch a screen all day.
Categories matter, though. An index fund or large-cap fund behaves very differently from a small-cap or sectoral one. Debt funds sit at the safer end and hybrid funds mix both. Picking a category that fits your time horizon counts for more than chasing last year’s top performer. Costs also add up: direct plans carry lower expense ratios than regular plans, and that gap compounds quietly. And as every factsheet reminds us, mutual fund investments are subject to market risk and past returns guarantee nothing.
Also Read: FD VS Mutual Funds
Stock Market Investment India: Control Comes With Responsibility
Direct stock market investment India appeals to people who enjoy research and want to choose their own businesses. Done well, it can beat pooled products over long stretches, because you decide what to hold and when to sell, and no fund expense ratio trims your return.
The flip side is real. A portfolio of five or six shares can lose a large chunk of value if a couple of bets go wrong. Company-specific problems, governance lapses and sudden earnings misses are things a diversified fund absorbs far more gracefully. Time is another cost. Reading annual reports, tracking results and staying calm through a sharp fall is practically a second job.
Beginners often frame mutual funds vs stocks as a contest with one winner. In practice, many seasoned investors hold both: a core of diversified funds and a smaller portion in stocks they have studied themselves.
Gold vs Stocks vs Mutual Funds: Side-by-Side Comparison
The table below puts the three options next to each other on the points that matter most to a first decision.
| Factor | Gold | Mutual funds | Direct stocks |
| Main role | Protection and diversification | Steady, diversified wealth building | Higher-growth, self-directed investing |
| Risk level | Low to moderate; price can stay flat for years | Varies by category, from low (debt) to high (small-cap) | High, especially with few holdings |
| Where returns come from | Price movement only | Growth or interest of the underlying portfolio | Price gains plus dividends, if any |
| Effort needed | Minimal | Low; SIPs run on autopilot | High; research and monitoring |
| Liquidity | High for ETFs; lower for jewellery | Usually a few working days to redeem | High on market days |
| Best suited for | Hedging, wedding or long-term reserve | Long-term goals, first-time investors | Experienced investors with spare capital |
Compare gold vs stocks over any single year and the winner is hard to predict. Over decades, history suggests equities have generally outpaced gold in India, though nothing guarantees that pattern will repeat. Gold, meanwhile, has often done its best work in the years when equities disappointed. That tendency to move differently is the reason many investors hold both rather than choose one.
The mutual funds vs stocks comparison comes down to effort and concentration. Funds spread your risk and save time. Stocks give you control, but you carry the full weight of every decision.
What to Check Before You Choose
Your time horizon. Money needed within two or three years should not sit in equity, whether through funds or shares. A sharp fall right before you need the cash is hard to recover from. Long goals such as retirement or a child’s education can handle more volatility.
Your real risk tolerance. Everyone is brave when markets rise. Ask yourself how you would react if your stock market investment India lost a fifth of its value in a few months. If the honest answer is panic, lean toward diversified funds and a gold allocation.
Taxes. Equity, equity funds and gold are taxed differently, and the treatment depends on the form of gold you hold and how long you hold it. These rules have been revised in recent years, so confirm the current rates and holding periods, or speak to a tax adviser, before selling.
Costs. Making charges on jewellery, expense ratios on funds and brokerage on shares all reduce what you keep. Small percentages matter over ten or fifteen years.
Your emergency fund. Before any of this, keep several months of expenses in a savings account or liquid fund. Without one, you may be forced to sell an investment at the wrong moment.
Best Investment Options 2026 for Different Situations
There is no single winner, so the smarter question is which mix fits your life. These are general examples, not personal advice.
- Salaried, just starting out: A monthly SIP in a diversified or index fund as the core, with a small slice in a gold ETF or gold fund. Simple, low-effort and easy to sustain.
- Conservative or nearing retirement: More weight on debt and hybrid funds, gold as a stabiliser, and only a limited equity portion through mutual funds rather than individual shares.
- Experienced, with time and spare capital: A mutual fund core plus direct stocks you have researched, using only money you can afford to see fluctuate.
- Saving for a wedding or purchase in two to three years: Avoid heavy equity exposure. Gold ETFs, debt funds or fixed-income options suit a short window better.
As a rule of thumb, many planners keep gold to a modest share of the total portfolio, often somewhere between 5 and 15 percent. That is a starting point for discussion, not a rule.
Final Verdict
The honest answer to gold vs mutual funds vs stocks 2026 is that they are not rivals. Gold is your shock absorber, mutual funds are your steady engine, and direct stocks are the optional accelerator for those with the time and temperament for it.
If you are undecided, a sensible starting point is a diversified mutual fund SIP as the base, a modest gold allocation for stability, and direct shares only after you are comfortable with the first two. Revisit the mix once a year, keep an emergency fund untouched, and verify current tax rules and prices before acting. This article is for general information and is not personalised financial advice.
Frequently Asked Questions
1. Which is best for beginners in the gold vs mutual funds vs stocks 2026 debate?
For most beginners, mutual funds through a SIP are the easiest place to start because they offer diversification and need little monitoring. A small gold holding can be added for balance. Direct stocks are better tackled once you understand how markets behave.
2. Is gold investment 2026 still worth considering after prices have risen?
Gold’s role is diversification, not chasing recent gains. If you have little or no gold, building a modest position gradually is more sensible than buying all at once. Keep in mind that prices can stay flat or fall after strong runs.
3. Are mutual funds vs stocks really different in risk?
Yes. A diversified equity fund spreads money across many companies, so one bad result hurts less. A small stock portfolio is far more exposed to a single company. Some fund categories, such as small-cap or sectoral funds, can still be quite volatile.
4. Can I hold gold and stocks together?
Yes, and many investors do. In a gold vs stocks comparison, the two often behave differently, so holding both can smooth out the ride. Just decide the proportions in advance so you are not swayed by headlines.
5. How much should I put into mutual fund investment India each month?
There is no fixed figure. A common approach is to invest what remains after expenses and your emergency contribution, then raise the amount as your income grows. Consistency matters more than the starting sum.
6. Is stock market investment India suitable for small amounts?
You can start small, and fractional-style investing through funds or low-priced shares is possible. The real limit is diversification: with a very small sum, a mutual fund usually spreads risk better than a handful of shares.