Gold is easy to recognise. Choosing the right way to invest in it is not.
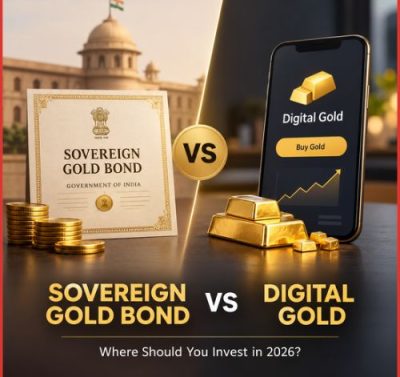
You can buy digital gold through an app in a few taps, sometimes starting with a very small amount. A Sovereign Gold Bond (SGB), by comparison, is a government security linked to the price of gold and comes with a completely different holding, interest, liquidity, and tax structure.
So, which is better: Sovereign Gold Bond or digital gold? The answer depends on what you value.
An SGB is a security issued under a government-backed framework, while commonly offered digital gold products are private-platform arrangements. In November 2025, SEBI specifically cautioned investors that such digital gold products operate outside its regulatory framework and can carry counterparty and operational risks.
The comparison, therefore, is not simply about which one tracks gold better. It is about what kind of gold exposure you are buying, who stands behind it, and what you need from the investment.
Sovereign Gold Bond vs Digital Gold at a Glance
| Factor | Sovereign Gold Bond | Digital Gold |
|---|---|---|
| Structure | Government security linked to gold | Gold purchased through a private digital platform |
| Gold exposure | Linked to the value of gold | Generally linked to the value of underlying gold |
| Interest | 2.5% per year on applicable SGB issues | No periodic interest |
| Minimum investment | Typically one gram for primary issues | Can usually be a very small amount |
| Tenure | Eight years, with premature redemption permitted after five years on specified interest-payment dates | No standard SGB-style maturity |
| Liquidity | Secondary market, maturity, or eligible premature redemption | Generally easier to buy and sell through the platform |
| Regulation | Government/RBI framework | Common digital-gold products are outside SEBI’s regulatory framework |
| Main additional risk | Market-price and liquidity risk when traded before maturity | Platform, counterparty, and operational risk |
| Tax | Depends on acquisition route and holding period; 2026 rules matter | Tax treatment differs from SGBs |
SGBs carry a fixed interest rate of 2.5% per year on the nominal value under the scheme terms, have an eight-year maturity, and permit premature redemption after the fifth year on applicable interest-payment dates. The important point is that SGB and digital gold are not simply two apps for buying the same thing.
What Is a Sovereign Gold Bond?
A Sovereign Gold Bond is a government security denominated in grams of gold. It gives investors exposure to changes in gold prices without requiring them to physically store gold. RBI documentation provides for a basic denomination of one gram, an eight-year tenor, and premature redemption from the fifth year on interest-payment dates.
An SGB has two potential sources of return: movement in the gold price, plus interest. Applicable SGB issues carry a fixed 2.5% annual interest rate, paid half-yearly on the nominal value. That makes SGBs different from simply holding gold. You are not buying jewellery, coins, or bars — you are holding a financial security whose value is linked to gold.
What Is Digital Gold?
Digital gold is designed to make gold investing as simple as an online purchase. A user selects an amount, pays through an app, and receives a digital representation of the gold purchased. Providers generally state that corresponding physical gold is held in vaults or through custodial arrangements, with the investor able to sell the holding or request delivery subject to the provider’s terms.
The attraction is straightforward: you can invest a small amount without purchasing a full gram or handling physical gold. However, convenience comes with a distinction that many first-time investors miss. Popular does not mean regulated.
SEBI’s November 2025 investor caution stated that digital gold or e-gold products offered by online platforms are different from SEBI-regulated gold products. It said such products are neither notified as securities nor regulated as commodity derivatives, and may expose investors to counterparty and operational risks. SEBI also said its securities-market investor-protection mechanisms do not apply to these products.
That does not automatically make every digital-gold provider unreliable. It does mean investors should understand the contractual and operational risks instead of assuming that an app interface provides the same protection as a regulated security.
The Biggest Difference: What Are You Actually Trusting?
This is where the SGB vs digital gold comparison becomes more meaningful. With an SGB, the investor is buying a security issued by the Reserve Bank of India on behalf of the Government of India under the SGB framework. With digital gold, the investor is dealing with a private platform and the entities responsible for sourcing, storing, and fulfilling the gold according to their terms.
So the risk structure is different. An SGB rests on a government-backed security framework, while digital gold rests on a platform and underlying-provider arrangement. That distinction matters more than the fact that both products are linked to gold prices.
Which Gives Better Returns?
There is no guaranteed winner, because both are exposed to changes in gold prices. But SGBs have a structural advantage that digital gold generally does not: interest income.
Suppose gold appreciates over a period of time. An eligible SGB investor may receive capital appreciation plus 2.5% annual interest. A digital-gold investor generally depends primarily on gold-price appreciation, minus applicable costs and spreads.
This does not mean SGBs will always produce a higher actual return. An SGB bought in the secondary market can trade at a premium or discount to its underlying redemption value, and liquidity may also differ between bonds and digital-gold platforms. The better comparison, then, is not simply which one has higher returns — it is which structure offers the better risk-adjusted outcome for your holding period and objective.
Why SGB Availability Matters in 2026
This is where the 2026 comparison differs from older gold-investment articles. Investors should not assume that a fresh SGB issue is continuously available. The RBI’s current SGB information is heavily centred on outstanding bonds, including schedules and prices for premature redemption and final redemption of existing series.
That creates three distinct situations:
- Existing SGB holder. You already own the bond and can follow its maturity or eligible premature-redemption schedule.
- Secondary-market buyer. You purchase an existing SGB through the market, subject to market pricing, liquidity, and tax considerations.
- New subscriber. You can subscribe directly only when an appropriate primary issue is announced.
Therefore, asking “Should I invest in SGB?” 2026 is incomplete without first asking whether you can access a fresh issue, or whether you’re considering a secondary-market SGB instead.
SGB vs Secondary-Market SGB: Why It Matters
Buying an SGB on the exchange is not necessarily equivalent to subscribing to a new issue. A secondary-market buyer needs to examine the current market price, the remaining maturity, the interest payable on that specific bond, its trading liquidity, the purchase price relative to the bond’s eventual redemption value, and the applicable tax treatment.
This distinction became particularly important after the 2026 tax changes. The Finance Bill’s memorandum states that the SGB capital-gains exemption at maturity is intended to apply where the bond was subscribed to by the individual at the time of original issue and held continuously until maturity. The amendment takes effect from April 1, 2026. Investors should therefore not assume that buying an SGB from another investor provides exactly the same tax outcome as subscribing to it at the original issue.
Taxation in 2026: The Detail Investors Should Not Ignore
Tax treatment is one of the areas where blanket statements can become misleading. For an SGB, at least three situations need to be separated.
Direct subscription and maturity is the clearest case — the 2026 tax amendment specifically addresses exemption for qualifying direct subscribers who hold the bond continuously until maturity. Sale or transfer before maturity is different again; the tax treatment can vary depending on the manner and timing of the transaction. And a secondary-market purchase requires the investor to assess the tax implications of acquiring the bond from another holder, rather than assuming the original subscriber’s treatment applies.
Interest on SGBs has historically been taxable under the applicable income-tax provisions. Digital gold has its own tax treatment, which should be checked under the tax rules applicable at the time of sale. Because tax rules can change, investors should verify the current provisions before making a substantial investment.
Which Is Safer: SGB or Digital Gold?
On regulatory structure, SGBs have the clearer advantage. They operate under the government and RBI framework, and existing SGB series continue to have formal redemption mechanisms and published redemption information.
SEBI, on the other hand, has explicitly warned that common digital gold products offered on online platforms fall outside its regulatory framework and may involve counterparty and operational risks. This leads to an important principle: ease of access is not the same as investor protection. For someone choosing purely on structural safety and regulatory oversight, digital gold should not be treated as equivalent to a regulated gold-market product.
Which Is More Convenient?
This is where digital gold has a genuine advantage. Buying digital gold can be extremely simple — open the app, choose an amount, pay, and hold. There is no need to wait for a government issue window, and you can also make very small purchases, which can make gold exposure accessible to people with limited investible funds.
SGBs are less flexible. A primary issue depends on availability, and an existing bond may need to be sold through the secondary market or held until an eligible redemption opportunity. So the trade-off is fairly clear: digital gold wins on convenience, while SGBs can win on investment structure and long-term economics.
Liquidity: Which Is Easier to Sell?
Digital gold is generally designed for easy platform-based transactions. The investor can usually sell through the same provider, subject to its terms.
SGB liquidity is more complicated. An investor can potentially hold the bond until maturity, use the eligible premature-redemption route after five years, or sell the bond on the secondary market. RBI’s SGB framework specifies eight-year maturity and premature redemption after the fifth year on interest-payment dates, though secondary-market liquidity itself can vary. An SGB may therefore be a better long-term instrument while being less convenient for someone who expects frequent transactions.
SGB vs Digital Gold: Which Is Better for Different Investors?
| Investor profile | More suitable starting point |
|---|---|
| Wants long-term gold exposure | SGB, where suitable and available |
| Wants very small purchases | Digital gold |
| Prioritises convenience | Digital gold |
| Wants interest in addition to gold exposure | SGB |
| Prioritises regulated investment products | SGB or other regulated gold products |
| Wants frequent platform-based transactions | Digital gold |
| Considering secondary-market SGBs | Compare price, liquidity, and tax carefully |
These are not universal prescriptions. An investor’s time horizon, risk tolerance, liquidity requirements, and overall portfolio should determine the final choice.
Should You Choose Digital Gold at All?
Before making the decision, there is an important third step: do you actually need digital gold at all?
SEBI has highlighted regulated gold alternatives, including Gold ETFs, exchange-traded commodity derivatives, and Electronic Gold Receipts (EGRs). This matters because the choice is not necessarily SGB versus digital gold — it can also be SGB versus Gold ETF versus another regulated gold product. For investors who want exchange-traded liquidity and a SEBI-regulated structure, Gold ETFs may deserve consideration alongside SGBs. The right gold product depends on the purpose of the allocation.
Common Mistakes Investors Should Avoid
- Assuming digital gold is SEBI-regulated because it appears inside a familiar financial app.
- Treating all SGB purchases as tax-equivalent after the 2026 rule changes.
- Buying a secondary-market SGB without checking its market price and remaining maturity.
- Looking only at gold-price returns and ignoring interest, spreads, and transaction costs.
- Assuming an SGB is always available for fresh subscription.
- Buying digital gold without understanding the provider’s custody and redemption arrangements.
- Treating recent gold-price gains as proof that gold will continue rising.
- Putting an excessive share of a portfolio into one asset simply because it has performed well recently.
How to Choose Between SGB and Digital Gold
A simple decision framework can help here.
Consider an SGB when you want long-term gold exposure, value the government-backed security structure, and can work with the available issuance, redemption, or secondary-market conditions. Consider digital gold when your priority is convenience, small-ticket investing, and easy platform-based transactions, and you understand the additional platform and regulatory risks involved. And consider regulated alternatives, such as Gold ETFs, when your objective is gold exposure with exchange-based liquidity or a SEBI-regulated investment structure.
The right question is not which gold product is trending. It is which structure fits the role gold is supposed to play in your portfolio.
The Bottom Line
Sovereign Gold Bonds and digital gold may follow the same underlying gold market, but they are fundamentally different investments. SGBs offer a government-backed security structure, exposure to gold prices, and interest on applicable issues — their long-term nature, availability, and the 2026 tax changes all need to be considered carefully. Digital gold offers convenience and very low entry barriers, but SEBI has warned that common digital-gold products offered online sit outside its regulatory framework and may expose investors to counterparty and operational risks.
For a long-term investor seeking gold exposure, an eligible SGB can be attractive where the acquisition route and tax treatment work in their favour. For someone who values flexibility and small-ticket purchases, digital gold may be more convenient, but convenience should not be confused with regulatory protection.
And in 2026, there is a final wrinkle: SGB availability and the way an SGB was acquired now matter more than they did in older comparisons. Gold may be the same asset. The investment wrapper is not.
Frequently Asked Questions
Is Sovereign Gold Bond better than gold for long-term investment in 2026?
Sovereign Gold Bonds can be a strong choice for long-term investors because they offer exposure to gold prices while also paying 2.5% interest each year on qualifying issues. In 2026, you also need to check whether a new issue is currently available or whether you’d be buying from the secondary market, since that affects both liquidity and tax treatment.
Is digital gold safe to invest in India in 2026?
Digital gold is easy to use, but the risks are worth understanding before you invest. SEBI has warned that many digital gold products sold by online platforms fall outside its regulatory framework and can carry counterparty and operational risks.
Can I buy Sovereign Gold Bonds in the market in 2026?
Yes, you can buy existing Sovereign Gold Bonds on the market if they are still available for trading. Before buying, check the current market price, how long the bond has left until maturity, the interest terms, how easily it can be resold, and the tax rules that apply to a secondary-market purchase.
Which is better for beginners in India: digital gold or Sovereign Gold Bonds?
Digital gold is usually simpler for beginners, since you can invest a small amount at any time without waiting for an issue window. Sovereign Gold Bonds may be the better fit for people who plan to hold the investment for several years and want both gold-price exposure and the additional annual interest.