Indian investors have spent the past two years putting record amounts of money into equities, mutual funds and systematic investment plans. Yet the returns from the headline stock-market indices tell a very different story from the strong bull run that preceded this period.
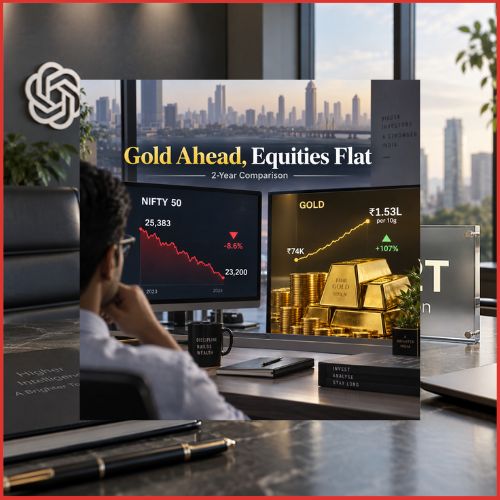
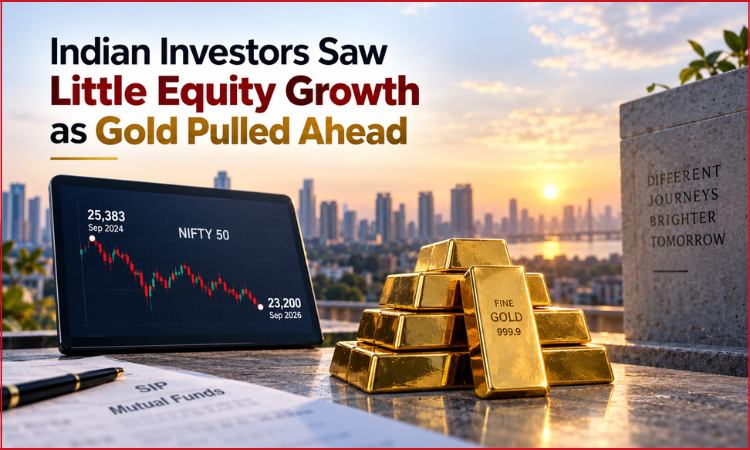
For someone who simply bought the benchmark index around September 2024 and held on, the outcome has been disappointing. The Nifty 50 closed at 25,383.75 on September 16, 2024. Two years later, it was trading around the 23,200 level, leaving the index roughly 9% below where it started.
That makes Indian investor returns over this period much more complicated than the steady rise in demat accounts and SIP contributions might suggest.
Two Years of Market Movement Led Backwards
September 2024 looked very different for Indian equities.
The Nifty 50 was trading above 25,000 and repeatedly reaching record levels. Investors who had enjoyed the post-pandemic rally were still accustomed to strong annual gains, while mid-cap and small-cap stocks had attracted enormous interest.
Two years later, the benchmark is below those levels.
The journey was hardly calm. Markets moved through rallies, corrections and repeated attempts at new highs. The Nifty even crossed 26,000 during the period.
But an investor who bought the index near September 2024 levels and simply checked the value today would still be sitting on a nominal loss.
That is the uncomfortable part of Nifty 50 returns over the past two years: a market can remain active, produce plenty of trading opportunities and still generate little wealth for an investor who entered at the wrong point in the cycle.
SIP Investors Had a Different Experience
Not every investor received the same result.
Someone investing a lump sum near the 2024 peak faced a very different outcome from an investor putting a fixed amount into the market every month.
SIPs naturally spread purchases across different market levels. When stocks fall, the same monthly contribution buys more units. When markets rise, it buys fewer.
That does not guarantee a positive return, but it can soften the effect of entering at an expensive level.
This helps explain why monthly SIP contributions have remained strong even though equity market returns have been muted.
Indian households have continued shifting savings towards mutual funds, suggesting that many retail investors are treating equity investing less like a short-term trade and more like a long-term financial habit.
Still, patience has been tested.
Investors who became accustomed to seeing double-digit gains during earlier years have had to adjust to portfolios that barely moved, or in some cases fell.
Mid- and Small-Caps Did Not Move Together
The headline index also hides what happened underneath it.
Indian equities have not behaved like one single market.
Large-cap shares struggled for long stretches, while certain mid-cap and small-cap companies continued delivering gains. Other pockets that had previously attracted heavy retail interest suffered steep corrections after valuations became difficult to justify.
That created a wide gap between investor outcomes.
Two people who both said they were invested in Indian equities could have ended the period with completely different returns depending on whether they owned an index fund, active mutual funds or individual shares.
Sector selection mattered as well.
Technology, public-sector companies, financial stocks, industrial businesses and consumer companies all went through different cycles during the period.
Simply saying “the market was flat” therefore does not capture what actually happened inside investor portfolios.
Gold Was the Clear Winner
The contrast with gold is much harder to ignore.
Around September 2024, 24-carat gold in India was priced at roughly ₹73,000-₹75,000 per 10 grams.
By September 2026, the price had climbed to around ₹1.53 lakh per 10 grams.
In other words, gold returns over the same broad two-year period were dramatically stronger than the performance of India’s benchmark equity index.
Gold more than doubled in rupee terms while the Nifty moved backwards.
For investors who maintained even a modest allocation to the metal, that difference would have had a noticeable effect on overall portfolio performance.
The move also demonstrates why comparing asset classes only during strong equity markets can give investors an incomplete picture.
Assets rarely lead at the same time.
Fixed-Income Investors Also Had Something to Show
Equity investors were not only competing with gold.
Traditional savings products offered returns that looked relatively attractive once stock-market performance weakened.
Public Provident Fund investments have continued offering rates above 7%, while National Savings Certificates have offered around 7.7%. Some government-backed savings schemes have carried rates above 8%.
Those returns look modest during a strong bull market.
But when the benchmark equity index produces a negative two-year outcome, stable fixed-income returns suddenly look far more competitive.
An investor earning 7% to 8% annually without experiencing stock-market volatility may have finished the period ahead of someone who bought the Nifty near its 2024 highs.
That does not mean fixed income will outperform equities over every long period. It simply shows how strongly the starting point affects short-term outcomes.
Inflation Makes the Difference Even Bigger
Headline returns also do not tell investors how much purchasing power they actually gained.
A portfolio that rises 5% when living costs also increase is not producing the same real improvement in wealth as the headline number suggests.
This distinction becomes particularly important during periods of low market growth.
When an equity portfolio rises 20%, smaller costs may not feel significant. When returns are close to zero, the same costs become much more visible.
That means the real experience of Indian investor returns over the past two years may have been weaker than the nominal market numbers suggest.
Entry Price Still Matters
The past two years offer a reminder that strong companies, growing SIP participation and a positive long-term economic story do not automatically guarantee strong returns from every starting point.
Price matters.
Investors who entered after several years of rising markets were buying at very different valuations from those who invested during earlier corrections.
Markets can spend years allowing earnings to catch up with prices.
That appears to be part of what investors have experienced since 2024.
India’s participation in equity markets continues to expand, and domestic investors now play a much larger role in supporting market liquidity.
But the last two years show that participation and profitability are not the same thing.
For many investors, the biggest lesson has been simple: the asset that looked least exciting when equities were booming ended up doing much more of the heavy lifting once the stock-market cycle changed.