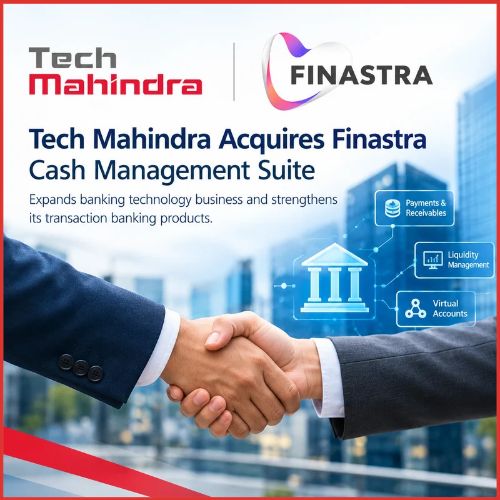
Tech Mahindra is making a more direct move into banking software by acquiring Finastra’s cash-management product suite, taking ownership of products that it previously helped customers implement.
The Tech Mahindra Finastra acquisition includes Fusion Cash Management, Fusion Virtual Accounts and Fusion Liquidity Management. Financial terms were not disclosed. Along with the core products, Tech Mahindra is taking over intellectual property and capabilities covering APIs, payables, receivables, cash-flow forecasting, liquidity management, virtual accounts and transaction reporting.
Experienced product-engineering and customer-success employees will also move to Tech Mahindra, helping the company continue supporting banks already using the platforms.
That continuity is important. Cash-management systems are deeply embedded inside bank operations, and customers cannot simply switch them off while ownership changes.
Tech Mahindra Was Already a Finastra Partner
The deal did not begin with two companies that barely knew each other.
Tech Mahindra and Finastra announced a broader strategic partnership in 2024.
Under that arrangement, Tech Mahindra became the exclusive global implementation partner for Finastra’s Cash Management platform and a preferred partner for Trade Innovation and Corporate Channels in Europe and the Americas.
In practical terms, Tech Mahindra was already helping banks deploy and modernise these systems.
The acquisition changes that relationship.
Instead of only implementing the software, Tech Mahindra now owns the Finastra Cash Management productsthemselves.
That gives the Indian IT company considerably more control over development, pricing, product road maps and future innovation.
Three Main Products Sit at the Centre of the Deal
Fusion Cash Management handles functions such as payments, receivables, reporting and corporate cash positions.
Fusion Virtual Accounts allows banks to create virtual account structures that help corporate customers organise payments and reconcile transactions more efficiently.
Fusion Liquidity Management focuses on how companies and financial institutions manage available cash across accounts and entities.
Those functions may not attract the attention that consumer banking apps do, but they are critical to large companies.
A multinational business may hold money across dozens of bank accounts, currencies and subsidiaries.
It needs to know where that cash is, whether it can be moved, what payments are due and how much liquidity will be required tomorrow.
That is the market Tech Mahindra is entering more directly through its cash management software acquisition.
Banks Want Real-Time Visibility Into Corporate Cash
The underlying market is changing quickly.
Corporate treasurers increasingly expect their banks to provide real-time cash positions rather than end-of-day reporting.
They want automated payables and receivables, API connections into internal treasury systems and better forecasting.
Banks, in turn, need software that can deliver those services while meeting security and compliance requirements.
Tech Mahindra says the acquired portfolio will help it address demand for real-time liquidity visibility, automated transaction processing and API-enabled treasury connectivity.
That makes the transaction more than a straightforward software purchase.
The company is buying a product layer that sits inside a much larger banking-technology relationship.
The Deal Gives Tech Mahindra More Intellectual Property
Large Indian IT companies have historically generated most of their revenue by providing services.
They supply engineers, consultants, cloud migration, cybersecurity, application support and business-process work.
Owning products changes the economics.
A software product can be sold to multiple institutions and developed centrally rather than requiring every dollar of revenue to be tied directly to additional employee hours.
That does not automatically make products more profitable. Development, sales and support can still be expensive.
But an IP-led banking platform gives Tech Mahindra a different route to growth alongside traditional consulting and outsourcing.
The company specifically described the acquisition as a foundation for product-led growth across transaction banking.
Existing Customers Are Central to the Transaction
Tech Mahindra is not buying an empty code base.
The deal brings an installed customer base with it.
That reduces one of the hardest problems in enterprise software: finding large financial institutions willing to become the first users of a platform.
Those banks are already running Finastra’s products.
The immediate task is therefore continuity.
Tech Mahindra has said customers will retain platform access, services and support as ownership changes. Product-engineering and customer-success talent is moving with the portfolio to reduce disruption.
Finastra’s Ruchir Purwar said Tech Mahindra’s existing banking expertise and familiarity with the products were important reasons it was well placed to take the suite forward.
BFSI Is Already Important to Tech Mahindra
The acquisition also fits the company’s broader financial-services push.
Tech Mahindra has been trying to expand beyond its historical strength in telecommunications and build more scale in banking and financial services.
Its latest Q2 numbers showed the wider company in a stronger position.
Revenue reached ₹16,180 crore, up 15.6% year on year. EBIT increased 40.5% to ₹2,387 crore, while net profit rose 32.7% to ₹1,586 crore. New deal wins reached $1.023 billion.
The company is also close to its FY27 target of a 15% EBIT margin, having reported 14.8% in the September quarter.
That gives Tech Mahindra a healthier base from which to invest in banking technology products.
Cash Management Can Open Doors to Adjacent Banking Work
The real value of the transaction could extend beyond the three named platforms.
Once Tech Mahindra owns technology used inside a bank’s transaction-banking operation, it has more opportunities to sell related services.
That could include cloud modernisation, integration, analytics, cybersecurity, AI, treasury connectivity and ongoing managed services.
The company also pointed to adjacent areas such as supply-chain finance and cash-flow forecasting.
This creates a “land and expand” opportunity.
A customer using one product can potentially add more modules or services without beginning a completely new vendor relationship.
For Tech Mahindra, that matters because global banking customers tend to be large, long-duration accounts.
AI Could Eventually Become Part of the Product Road Map
Tech Mahindra has not presented the acquisition primarily as an AI deal.
Still, the direction is fairly obvious.
Cash forecasting is one area where better models can help companies estimate future liquidity needs.
AI can also assist with payment exceptions, reconciliation, anomaly detection and identifying unusual transaction patterns.
Tech Mahindra has been investing aggressively in AI across its wider business, so integrating those capabilities into the acquired portfolio would be a natural next step.
The challenge will be doing so carefully.
Banking software handles sensitive financial information and mission-critical transactions. New automation cannot come at the expense of reliability, explainability or compliance.
This Is a Different Kind of Growth Bet
The financial size of the deal remains unknown because neither company disclosed the consideration.
That limits how far investors can judge the immediate return on the acquisition.
Strategically, though, the direction is clearer.
Tech Mahindra is moving from being an implementation partner to owning the Finastra cash management suite itself.
It gains intellectual property, existing customers, experienced employees and a platform it can keep developing.
For banks, the most immediate question will be whether the handover is smooth.
For Tech Mahindra, the bigger test comes afterwards: whether it can use those products to generate recurring software revenue and win a larger share of the global transaction-banking technology market.