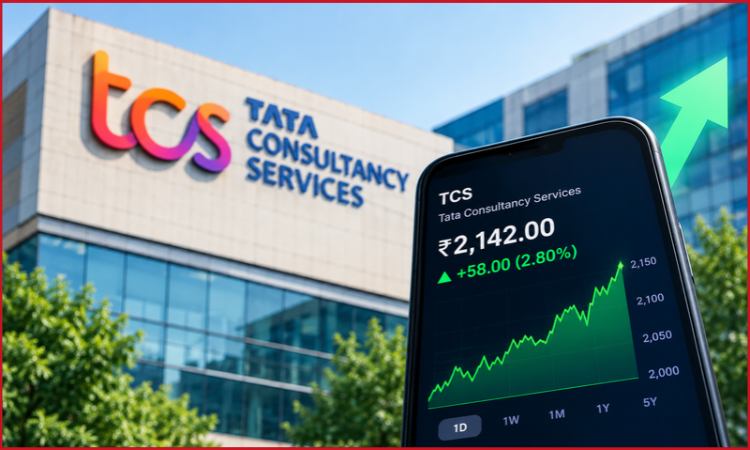
Tata Consultancy Services shares climbed nearly 3% on Thursday morning, bucking a weak broader market as investors positioned themselves ahead of the IT major’s September-quarter earnings.
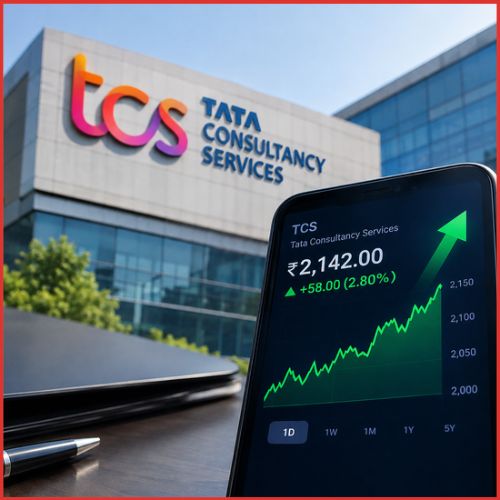
TCS shares touched ₹2,142 on the BSE during intraday trading, up 2.8% from the previous close of ₹2,084. The stock later gave back some of those gains but remained higher in morning trade.
The enthusiasm does not necessarily mean investors are expecting a blockbuster quarter. Brokerage estimates point to fairly modest sequential growth. What the market wants to hear is whether demand is finally beginning to improve after a difficult period for large Indian IT companies.
TCS Rises While the Broader Market Slips
The contrast was noticeable during Thursday’s opening session.
At around 9:50 am, TCS was trading close to ₹2,124, up about 1.9%, while the Sensex was down more than half a percent.
Other IT names joined the move. HCL Technologies, Tech Mahindra and Wipro also traded higher, helping lift the Nifty IT index even as the wider market remained under pressure.
That makes the rally less about TCS alone and more about traders taking positions ahead of the beginning of the September-quarter IT earnings season.
TCS reports first among the major software exporters, so its numbers and management commentary often shape sentiment towards the rest of the sector.
Revenue Growth May Look Better Year on Year
On paper, the year-on-year numbers should show healthy growth.
JM Financial expects TCS Q2 revenue to reach roughly ₹73,110 crore, an increase of 11.1% from the corresponding quarter last year.
Kotak Institutional Equities has a similar view, expecting rupee revenue to grow around 11.4%.
Those figures look strong at first glance.
The sequential picture is much quieter.
Brokerages expect constant-currency revenue growth of only about 0.5% to 0.6% from the June quarter. That is hardly the kind of acceleration investors would normally expect from what is traditionally a seasonally stronger period for IT services.
The difference between the annual and quarterly numbers is why management commentary will matter so much after the results are released.
Investors Want to Know Whether Client Spending Is Improving
Large IT companies have spent several quarters dealing with hesitant customers.
Clients continue to sign technology contracts, but discretionary work has been slower to return. Companies have been more careful about launching large transformation projects when economic conditions remain uncertain.
That tension is likely to remain one of the biggest questions around the TCS Q2 results 2026.
Investors will want to know whether AI is creating enough new revenue to offset pricing pressure elsewhere.
Margins May Improve Slightly From the Previous Quarter
Profitability will be another closely watched number.
JM Financial expects TCS to report EBIT of around ₹17,609 crore, up 6.3% year on year.
Its estimate puts the EBIT margin at about 24.1%, a small improvement sequentially but roughly 110 basis points below last year’s level.
Other brokerages are slightly more optimistic about the quarter-on-quarter improvement.
The reason is fairly straightforward. The effect of annual wage increases should become less severe after weighing on the previous quarter.
But TCS still has other pressures to absorb.
Pricing remains competitive, acquisitions have costs attached to them and the company continues to invest in AI and other growth areas rather than allowing every efficiency gain to flow directly into margins.
Profit Could Reach About ₹13,700 Crore
JM Financial expects net profit of around ₹13,702 crore.
That would represent an increase of 13.5% from a year earlier, although profit could slip slightly compared with the June quarter.
Other estimates are in roughly the same range.
The market will probably look beyond the headline profit number unless it differs sharply from expectations.
For an IT company of TCS’s size, one quarter of earnings rarely changes the long-term story on its own. Investors are more interested in what the numbers say about demand over the next several quarters.
That brings deal wins into focus.
Deal Bookings Could Be the More Important Number
Brokerages expect TCS to report another sizeable contract pipeline.
JM Financial sees total contract value in the range of $8 billion to $10 billion, while other estimates stretch towards $11 billion.
The recently announced Porsche contract will attract particular attention.
Investors will also be listening for an update on the next phase of work with BSNL and when those projects are likely to begin contributing meaningfully to revenue.
Strong deal wins are useful, but they do not always translate into sales immediately.
Large contracts can take several quarters to ramp up.
The question for TCS investors is therefore not only how much business the company signs, but how quickly that business begins appearing in reported revenue.
AI Revenue Will Be Closely Watched
TCS has been talking increasingly about the size of its AI business.
That figure matters because investors are trying to understand whether generative AI is becoming a meaningful new revenue stream for Indian IT services companies or mostly changing how existing projects are delivered.
Demand is coming from areas such as AI-led modernisation, cybersecurity, autonomous business operations and cloud infrastructure.
If those businesses continue expanding quickly, they could provide an important counterweight to slower traditional outsourcing work.
The downside is that AI can also allow companies to complete some projects using fewer people.
That is why investors are unlikely to be satisfied by a simple statement that AI demand is strong. They will want numbers showing how that demand is translating into contracts and revenue.
TCS Stock Has Already Had a Difficult Year
Thursday’s rally comes after a fairly painful stretch for shareholders.
TCS had corrected about 14% during August alone before finding support around ₹2,000.
The stock has since spent time moving within a relatively narrow range.
Technical analysts see ₹2,000 as an important near-term floor. As long as the stock stays above it, some see room for a recovery towards roughly ₹2,250-₹2,300.
A move below ₹1,970 would weaken that setup.
Those levels are useful for short-term traders, but today’s earnings could easily change the picture once the actual numbers and management outlook are known.
One Quarter Will Not Settle the IT Debate
The TCS share price rising ahead of results shows that investors are willing to look for a recovery.
Whether that optimism lasts depends on more than an 11% year-on-year revenue figure.
The market needs evidence that sequential growth is improving, big deals are turning into revenue and AI is creating new business rather than simply lowering the value of old work.
Margins need to hold up as well.
TCS has the scale, client relationships and deal pipeline to benefit when technology spending improves. The unresolved question is when that improvement becomes strong enough to show clearly in quarterly numbers.
Thursday’s results should provide another piece of that answer.
Source:
TCS shares jump 3% ahead of Q2 results; what to expect & how to trade?