Nokia’s latest quarter looks increasingly unlike the slow-growth telecom-equipment story investors had become accustomed to.
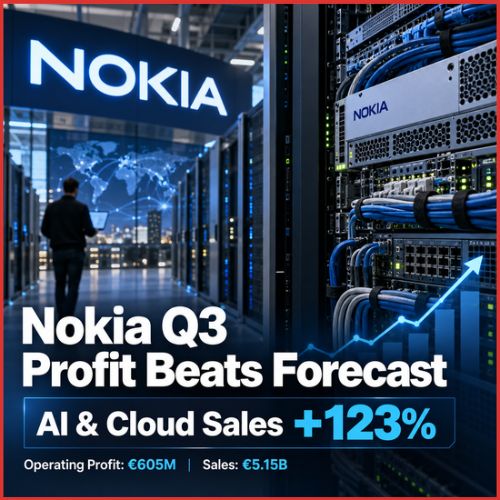
The Finnish company reported Nokia Q3 operating profit of €605 million for the September quarter, well above both last year’s result and analyst expectations, as spending by AI and cloud customers accelerated sharply.
Comparable operating profit rose from €448 million a year earlier. Analysts had expected only about €453 million.
Net sales also came in ahead of forecasts, reaching €5.15 billion.
Behind those headline numbers sits an even bigger change: sales to AI and cloud customers jumped 123% from a year ago.
Profit Beat Expectations by a Wide Margin
The difference between Nokia’s actual profit and the consensus estimate was substantial.
Comparable operating profit of €605 million was roughly one-third higher than the €453 million analyst forecast supplied by the company.
That is not the kind of beat created by a few million euros either way.
It points to better operating leverage as stronger sales move through parts of the business that are benefiting from data-centre and AI infrastructure demand.
A year earlier, comparable operating profit had been €448 million.
The rise therefore came alongside both revenue growth and an improvement in how effectively that revenue converted into profit.
For investors following Nokia earnings, that combination is much more encouraging than higher sales alone.
Net Sales Reached €5.15 Billion
Comparable net sales increased 10% to approximately €5.15 billion.
The market had expected around €5.05 billion.
On a constant-currency basis, growth was approximately 9%.
That gives Nokia a stronger Q3 than many traditional telecom-equipment investors might have expected at the beginning of the year.
Telecom carriers remain important customers, but the demand mix is changing.
Cloud operators and AI data centres increasingly require enormous amounts of high-speed networking capacity to move information between servers, accelerators and facilities.
That is creating an additional market for equipment suppliers that can provide optical and IP networking hardware.
AI and Cloud Sales Jumped 123%
This is where the quarter becomes considerably more interesting.
Nokia said AI and cloud customer sales grew 123% year on year.
Order intake from the same customer group increased 118% to €1.5 billion.
That second figure matters because orders provide an indication of business that has been secured but may not yet have appeared fully in revenue.
If those contracts convert as expected, AI and cloud could remain an important growth driver beyond the current quarter.
Nokia is benefiting from a part of the AI boom that receives less attention than chips.
GPUs cannot work effectively in large clusters unless data can move between them quickly.
That requires sophisticated networking.
AI Needs Networks as Much as Computing
The first phase of the AI infrastructure boom was largely discussed through processors.
Nvidia GPUs became the obvious symbol of the spending cycle.
The next constraint is increasingly the network around those processors.
Thousands of accelerators inside a data centre need to communicate with each other. Data must move between storage, compute clusters and sometimes separate facilities without creating bottlenecks.
That creates demand for high-performance Ethernet, routing and optical systems.
Nokia’s IP Networks and Optical Networks businesses sit directly inside that infrastructure layer.
The company is therefore getting exposure to AI capital spending without needing to manufacture the GPUs themselves.
IP Networks Grew Particularly Quickly
Network Infrastructure was one of the strongest parts of Nokia’s quarter.
Sales in the segment increased 15% year on year in constant currency.
Inside that, IP Networks grew approximately 43%.
Optical Networks increased around 18%.
Those are unusually strong growth rates for businesses historically associated with relatively mature telecommunications infrastructure.
The driver is changing because the customer base is changing.
Hyperscalers and other cloud operators are building networks capable of supporting huge AI workloads.
As those facilities become larger, the amount of networking equipment required grows along with computing capacity.
That helps explain the improving Nokia Network Infrastructure growth.
Nokia Expects More Growth in 2027
Management does not see the current AI demand as a one-quarter event.
Chief Executive Justin Hotard said Nokia expects its combined Optical and IP Networks businesses to grow between 25% and 30% in 2027.
That is a strong forecast.
It implies the company believes today’s orders are part of a larger infrastructure cycle rather than customers simply pulling purchases forward.
Order intake from AI and cloud buyers supports that view.
Still, forecasts depend on hyperscalers continuing to spend aggressively.
AI infrastructure programmes are enormously expensive, and any slowdown in data-centre construction would eventually affect networking suppliers as well.
For now, Nokia is seeing the opposite.
Nokia Is Also Bringing AI Into Telecom Networks
The company is not only selling infrastructure used by AI data centres.
Nokia is trying to bring artificial intelligence into telecommunications networks themselves.
A day before the earnings release, it announced additional work with Nvidia around AI-RAN and agentic network automation.
AI-RAN combines conventional mobile-network functions with AI computing at the edge.
The longer-term idea is that telecom infrastructure can become a distributed computing platform capable of supporting AI services closer to where data is generated.
That remains an emerging area.
It nevertheless shows Nokia’s AI strategy is developing on two sides: selling networks to AI infrastructure customers and adding AI capabilities inside telecom networks.
Nokia Shares Have Already Rerated
Investors have noticed the change.
Nokia shares are up around 48% in 2026.
That means the company’s improving fundamentals are no longer completely hidden in the valuation.
Strong AI growth can still support further earnings expansion, but expectations are higher after such a substantial share-price gain.
Investors will therefore be watching whether orders continue translating into sales and whether the rapid growth in IP and optical networking can hold.
A good quarter becomes harder to impress the market with once investors begin expecting good quarters regularly.
The AI Boom Is Spreading Beyond Chips
Nokia’s Q3 numbers offer a useful example of how broad the AI investment cycle has become.
The early beneficiaries were easy to identify: chip designers, semiconductor manufacturers and cloud platforms.
The spending is now spreading through the infrastructure stack.
Data centres need networking, power, cooling, fibre and software alongside processors.
Nokia has found itself in one of those less glamorous but increasingly valuable layers.
A 123% jump in AI and cloud sales is difficult to dismiss as a side business.
If order growth remains close to current levels, AI infrastructure could become one of the central drivers of Nokia’s next phase rather than simply an extra source of demand.
Q3 suggests that transition is already under way.