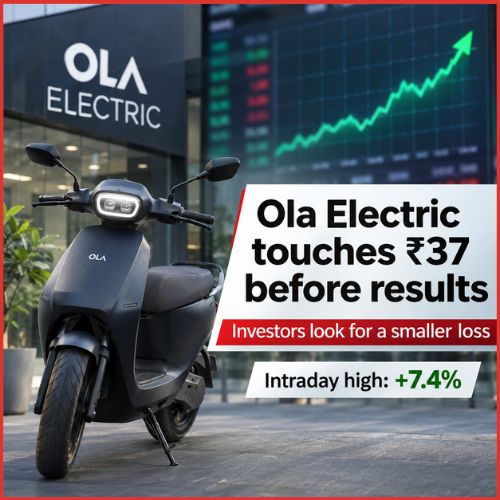
Ola Electric had not released its September-quarter numbers when buyers pushed the stock to ₹37 on November 12. The shares gained as much as 7.4% on the BSE in morning trading, reflecting expectations of improvement ahead of an earnings announcement due later that day.
Trading was busy. By 10:37 am, approximately 99.8 million shares had changed hands across the NSE and BSE combined. The Ola Electric share price subsequently stood at ₹36.19, up 5.08%, in the reported snapshot.
The distinction between those two prices matters. ₹37 was the intraday high, not the closing price. And the buying preceded the results, so it cannot be described as the market’s verdict on the September quarter.
What investors had available was a set of expectations: a possible increase in sales from the June quarter, narrower losses and some benefit from cost controls. Whether Ola delivered on those expectations remained to be seen.
A Better Quarter Would Still Leave Sales Below Last Year
Kotak Institutional Equities estimated net sales of about ₹507 crore for Q2 FY27. That would be an 11.5% improvement over the preceding quarter.
Against the same period a year earlier, however, it would represent a decline of 26.5%.
Both comparisons belong in the assessment. A business can begin recovering from a weak quarter while remaining well below its earlier level of activity. Calling the forecast an outright turnaround would get ahead of the evidence.
The brokerage expected volumes to fall around 20% year on year. It also projected a 5–6% reduction in average selling prices, linked to a weaker product mix.
For the Ola Electric Q2 FY27 results, the revenue explanation will therefore be as important as the total.
More deliveries would point to one kind of improvement. Higher revenue generated mainly through a change in the models sold would tell a different story. Discounts, pricing and the mix of vehicles can all affect the amount earned per unit.
The results need to show which of those factors shaped the quarter.
The Loss Forecast Gives Investors Something More Specific To Test
Kotak forecast a net loss of approximately ₹315.3 crore, narrower both year on year and compared with the previous quarter.
Its EBITDA-loss estimate was around ₹140 crore. The brokerage compared that with ₹200 crore for the corresponding period and ₹170 crore for the preceding quarter in its analysis.
These figures were forecasts. They were not losses Ola had already announced for September.
The brokerage expected help from cost controls, operating leverage and a higher contribution from the Gen-3 platform, with commodity pressures partly offsetting those benefits.
That provides a more useful framework than simply asking whether the loss became smaller.
If additional sales helped spread fixed expenses across more vehicles, the improvement would have an operating explanation. If procurement or production costs declined, those savings would deserve attention too.
But Ola Electric earnings also need to be read for costs that may have shifted between periods. A lower expense in one quarter is more valuable when it can be sustained without creating a larger bill later.
The accounts and management commentary should help separate those possibilities.
Nearly 100 Million Shares Traded Before The Answers Arrived
The volume by mid-morning showed how much attention the announcement had attracted. It did not reveal one shared reason behind every trade.
Some participants may have been buying in anticipation of better numbers. Others could have been adjusting existing positions or trading the price movement itself.
Every transaction has a buyer and a seller. Heavy activity shows that a large amount of stock changed hands; it does not establish that all those involved agreed on the company’s prospects.
The Ola Electric stock rally does change the immediate setting for the results.
Once the price has risen ahead of an announcement, the company is being judged against expectations that may already have improved. A smaller loss could still receive a muted response if investors had hoped for more.
The reverse is possible as well. Results can remain weak in absolute terms and still exceed what the market expected.
Thursday morning’s move therefore adds a question to the earnings discussion: how much improvement had buyers already allowed for?
The Chart Has Improved, But The Business Still Has To Deliver
Bonanza senior technical research analyst Virat Jagad described signs of recovery after Ola formed a base around ₹30–32.
The stock had moved above its 20-day, 50-day and 100-day exponential moving averages. Its relative strength index was around 55, suggesting firmer momentum.
There were qualifications. It remained below the 200-day EMA near ₹38, while ₹40–42 was identified as a further resistance area. The ₹35–36 range was described as near-term support.
Those levels describe an analyst’s reading of trading behaviour. They are not company forecasts.
They may help explain where the next contest between buyers and sellers develops. They cannot establish whether Ola sold enough vehicles, improved margins or reduced cash outflow during the quarter.
An earnings release can also change a chart quickly. New information gives investors a reason to reassess positions built using older assumptions.
Cash Use Will Matter After The Headline Loss
The loss figure will attract attention, but it will not answer every financial question.
Cash can move differently from accounting earnings. Inventory purchases, supplier payments and investment spending can affect how much money a company needs even when its reported loss narrows.
That makes the supporting disclosures important.
Investors will want to understand the relationship between production, deliveries and inventory. They will also need to assess whether cost reductions reflect lasting changes or the timing of expenditure.
Management’s account of demand and after-sales support will add context. A vehicle business has to deliver products and continue supporting the people who buy them.
The Ola Electric results preview offers a case for possible sequential progress. It remains a case built on estimates.
By the reported morning snapshot, buyers had shown a willingness to back that possibility. The next step belonged to the company: publish the numbers and explain what had improved, what had not, and how much of the change could carry into the next quarter.