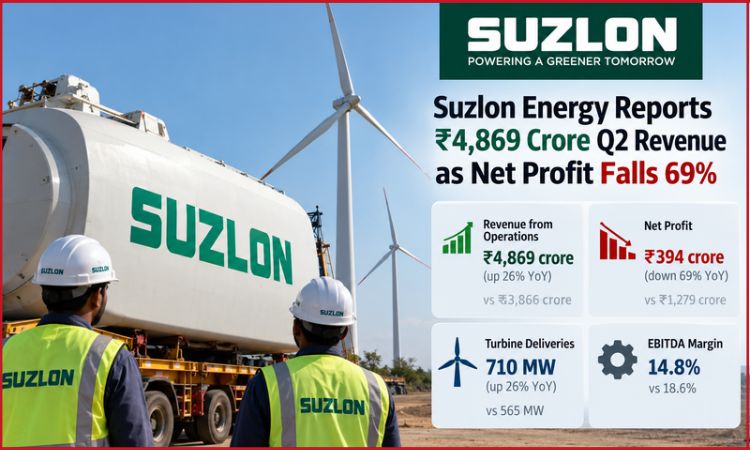
Suzlon Energy delivered more wind turbines and increased quarterly revenue by 26%, but the additional business brought little improvement in underlying profit. Its September-quarter results reveal a company expanding execution while facing pressure on the earnings generated from that growth.
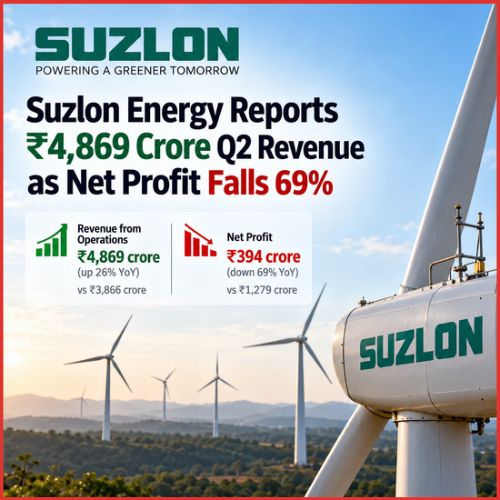
The wind energy company reported consolidated net profit of ₹394 crore for the second quarter of FY2026–27, down from ₹1,279 crore a year earlier. That 69% decline needs context: the previous year’s earnings included a substantial deferred tax benefit.
Revenue from operations reached ₹4,869 crore, compared with ₹3,866 crore in the corresponding quarter. Turbine deliveries rose to 710 megawatts, providing clear evidence of stronger activity. Yet operating earnings remained almost unchanged, leaving profitability as the central question behind an otherwise busy quarter.
Previous Tax Benefit Distorts the Profit Comparison
The sharp fall in reported net profit largely reflects an unusually strong comparison period. In the September quarter of FY2025–26, Suzlon recognised a deferred tax asset of approximately ₹891 crore, lifting its reported earnings considerably.
Excluding that impact, the previous year’s comparable net profit was about ₹389 crore. Against that figure, the latest ₹394 crore represents growth of roughly 1.3%.
This distinction changes how the results should be read. The business did not suffer a collapse in comparable net earnings of the scale suggested by the headline decline. However, adjusted profit growth was modest, particularly alongside a revenue increase of more than one quarter.
The tax adjustment explains the dramatic annual fall. It does not explain away the weaker relationship between sales growth and operating returns.
Higher Revenue Fails to Lift Operating Earnings
Earnings before interest, tax, depreciation and amortisation stood at approximately ₹720 crore, against ₹721 crore a year earlier. Suzlon therefore generated almost the same operating earnings from a substantially larger revenue base.
Its EBITDA margin narrowed to 14.8% from 18.6%, a reduction of 3.8 percentage points. Put simply, the company retained less operating profit from each rupee of revenue during the quarter.
Profit before tax also weakened, falling to ₹518 crore from approximately ₹563 crore. That decline provides another reason to look beyond the deferred tax comparison when assessing performance.
The figures suggest that higher volumes have yet to translate into stronger earnings efficiency. Suzlon’s expanding activity is visible in its sales, but the financial benefit of that expansion remains uneven.
Record Deliveries Show Execution Is Advancing
Operationally, Suzlon had a stronger quarter. Turbine deliveries reached a record second-quarter level of 710 MW, compared with 565 MW in the same period last year.
The increase of 145 MW represents growth of approximately 26%, broadly matching the rise in revenue. It indicates that the sales improvement was supported by higher equipment deliveries rather than being an isolated movement in the accounts.
Suzlon also commissioned 454 MW during the quarter. Deliveries and commissioning measure different stages of execution: supplying turbines advances an order, while commissioning brings a project into operation.
Chief executive Ajay Kapur highlighted both figures when discussing the results. Together, they show progress in moving projects through execution, although the margin figures demonstrate that completing more work does not automatically produce proportionately higher profit.
Business Segments Follow Different Earnings Paths
The contrast between revenue and profitability was particularly evident in Suzlon’s Renewable Energy Solutions business.
Revenue in that segment increased 30% to ₹4,212 crore. Its segment result, however, fell 22.5% to ₹371 crore. The company’s largest revenue contributor therefore expanded sales while reporting weaker segment earnings.
Renewable Energy Asset Management Services moved in the other direction. Revenue rose 11.2% to ₹640 crore, while its segment result increased 51.5% to ₹220 crore.
These movements help explain why group revenue alone gives an incomplete account of the quarter. Performance varied considerably across the business. Stronger services earnings provided support, while the larger solutions operation faced a decline in its segment result despite substantial sales growth.
For future quarters, the balance between these businesses will matter alongside the overall pace of deliveries.
Order Book Offers Visibility Beyond September
Suzlon ended the quarter with an order book exceeding 6 gigawatts. New orders secured during the first half of FY2026–27 surpassed 1.5 GW, giving the company further work to execute after its record quarterly deliveries.
Public sector undertakings and commercial and industrial customers accounted for 78% of the order book. That customer mix shows the importance of institutional and business demand to Suzlon’s current pipeline.
Engineering, procurement and construction contracts represented 38% of outstanding orders. The company is working towards increasing that share to 50% by FY2027–28.
A rising EPC contribution expands Suzlon’s involvement in project execution. It also makes delivery discipline increasingly important, because a broader scope of work brings more activities that must be coordinated before a project is completed.
The backlog supports revenue visibility. Its eventual contribution to earnings will depend on execution costs, project schedules and the margins achieved.
Management Keeps Attention on Cash and Capital
Alongside the operating update, Suzlon reported that its net worth had crossed ₹10,000 crore. CRISIL also upgraded the company’s long-term credit rating to AA-/Stable.
Those developments offer a separate measure of financial progress at a time when quarterly margins have weakened. They do not remove the pressure on profitability, but they broaden the assessment beyond the reported net profit decline.
Chief financial officer Rahul Jain referred to commodity and currency volatility while discussing the quarter. Management also emphasised manufacturing capabilities, execution, cash flow and disciplined capital allocation.
The next earnings reports will test whether those priorities produce better operating returns. Suzlon has demonstrated that it can deliver more equipment and maintain a sizeable order pipeline. The immediate challenge is to earn more consistently from that activity.
September’s results leave two clear findings: the reported profit decline was heavily affected by last year’s tax benefit, while the contraction in operating margin reflects a current business challenge. Revenue growth remains strong. Profit conversion now needs to catch up.
Source link supplied: Renewables Now — Suzlon Energy’s fiscal Q2 results.