Investors who checked their mutual fund portfolios at the end of October probably noticed something unusual. Large-cap funds, which had spent much of the year taking a back seat to other investment themes, suddenly looked like the stronger performers. Gold and silver, meanwhile, were heading in the opposite direction.
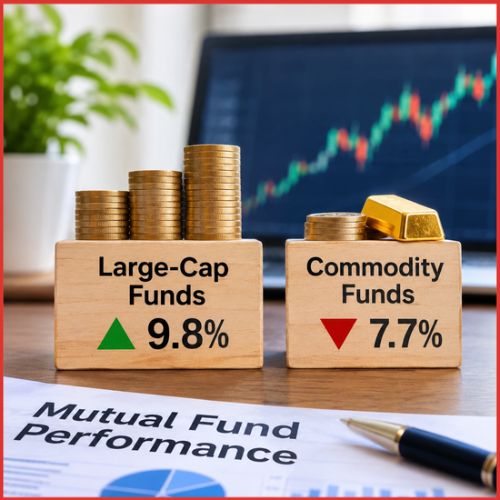
The difference was hard to miss. Large-cap equity funds delivered a 9.8% return during October 2026, while the commodities fund category recorded a median loss of 7.7%, according to data analysed by Vallum Capital Advisors using Morningstar figures.
The reversal came after a remarkable year for precious metals. Silver had gained 160% during 2025, and gold had risen 44%.
For people who entered these investments after watching last year’s rally, the latest performance would have been disappointing. Those who kept money in large Indian companies, however, had a much better October.
Gold and Silver Finally Run Into a Difficult Market
Gold has traditionally been viewed as a place to park money when financial markets become uncertain. Silver attracts similar interest, although its industrial uses also make it sensitive to changes in manufacturing demand.
Neither metal is immune to price corrections.
Silver’s decline was particularly severe compared with gold’s. That is not entirely surprising, given that silver often experiences larger price movements in both directions.
There is also an important distinction in the October numbers. The 7.7% fall refers to the median performance of commodity-focused funds covered in the analysis. It should not be confused with the exact change in the market price of physical gold.
Still, the broader message was clear. The enthusiasm surrounding precious metals had cooled considerably.
Investors Show a Clear Preference for Larger Companies
The domestic equity market told a rather different story.
Large-cap mutual funds gained 9.8% in October, comfortably ahead of mid-cap funds at 4% and small-cap funds at just 0.7%.
The gap says quite a bit about where investors were finding opportunities.
Large businesses generally have established revenue streams, wider access to capital and shares that are easier to trade in substantial quantities. Those characteristics can become appealing when investors are uncertain about valuations elsewhere.
It does not mean that smaller businesses suddenly lack growth potential. Rather, October suggested a greater willingness to pay for stability and established earnings.
The strength was not confined to one category. Large-and-mid-cap funds returned 6.8%, flexi-cap funds gained 6.2%, and multi-cap funds advanced 5.9%.
Taken together, the results show that investors were still willing to own equities. They were simply becoming more selective about which ones.
Fresh Investments Tell Another Part of the Story
Fund returns show what happened to investment values. Inflows provide a closer look at where new money was going.
Large-cap funds received ₹13,887 crore in October, up from ₹9,634 crore in September.
Small-cap funds continued attracting investments, but their inflows dropped from ₹8,071 crore to ₹5,152 crore over the same period.
That is a meaningful difference.
Money was not disappearing from the equity market. Total equity mutual fund inflows actually rose slightly, from ₹44,586 crore in September to ₹45,642 crore in October.
What changed was how investors distributed those investments.
Some may have wanted to reduce exposure to smaller companies after a period of uneven performance. Others may have considered large-cap valuations more attractive.
The figures cannot tell us precisely why each investor made a decision. They do, however, point towards a noticeable change in preference.
Banking Stocks Enjoy a Particularly Strong October
Banking and financial services funds were among the month’s standout performers, delivering a 9.3% return.
Public-sector bank funds did even better, climbing 14.6%. Broader banking funds gained 10%, while private-bank funds returned 9.7%.
For investors who had exposure to financial stocks, October offered a welcome improvement.
Healthcare funds also performed strongly, gaining 8.4%, while housing-opportunity funds recorded an 8.3% increase.
Healthcare’s performance was not just a short-lived October development. As of November 16, the category had generated a one-year return of 20.4% and an annualised three-year return of 21.9%.
Other sectors presented a less comfortable picture.
Technology funds gained 5.4% in October, yet remained down 11.2% for the year. Consumption funds returned 7.5% during the month but were still marginally negative on a year-to-date basis.
FMCG funds were facing an even tougher period, with losses of approximately 15% for the year.
That contrast is worth remembering. A good month can improve a fund’s recent performance without repairing all the damage from earlier declines.
A Surprising Turnaround in Money-Market Funds
One of October’s biggest shifts happened in a relatively less-discussed corner of the mutual fund industry.
Money-market funds attracted ₹88,740 crore in net investments after recording withdrawals of nearly ₹1.35 lakh crore during September.
The change amounted to approximately ₹2.23 lakh crore in a single month.
Much of September’s weakness had been linked to quarter-end liquidity requirements. October subsequently brought a considerable recovery.
Money-market funds commonly hold short-term debt instruments and are used by institutions and other investors to manage cash.
Fixed-income funds also showed improvement, although they remained in negative territory.
Their net outflows narrowed from ₹29,516 crore in September to ₹6,364 crore in October.
Both money-market and fixed-income funds generated returns of around 0.5% during the month.
The figures suggest that investors were not simply chasing higher equity returns. Liquidity management remained an important consideration, particularly for institutional participants.
Overseas Funds Struggle as Global Technology Shares Come Under Pressure
Investing internationally did not offer much relief in October. Japanese funds lost 6.1%, while emerging-market funds were down 9.5%.
European funds were an exception, managing a positive return of approximately 1%.
Part of the weakness came from selling pressure in technology-related investments. Currency movements added another complication.
The rupee strengthened against both the dollar and the euro during October. For Indian investors holding foreign assets, a stronger home currency can reduce returns once overseas investments are converted back into rupees.
This was a reminder that international investment carries two separate risks: the performance of the underlying asset and movements in exchange rates.
What Should Investors Take Away From October’s Performance?
October did not establish a permanent winner among equities, precious metals and debt instruments.
It showed how quickly their relative performance can change.
Vallum Capital’s analysis found that gold had almost no historical correlation with the Nifty 500 over the five-year period examined. Silver’s correlation was approximately 0.1, while long-term Indian bonds stood at around 0.2.
Those relationships help explain why investors spread money across different asset classes in the first place.
There will be periods when gold performs better than shares. At other times, equities may deliver the stronger returns. Debt investments can serve a different purpose altogether.
For investors reviewing their portfolios after October, the more useful question is whether their existing investments still match their financial goals.
Large-cap funds had an excellent month. Precious metals did not. Neither result is a reliable forecast of what will happen next.
With corporate earnings, global interest-rate expectations and overseas investment flows still influencing markets, the next few months could bring another change in leadership.