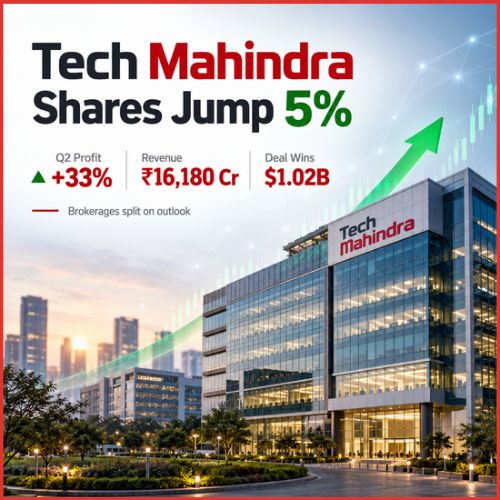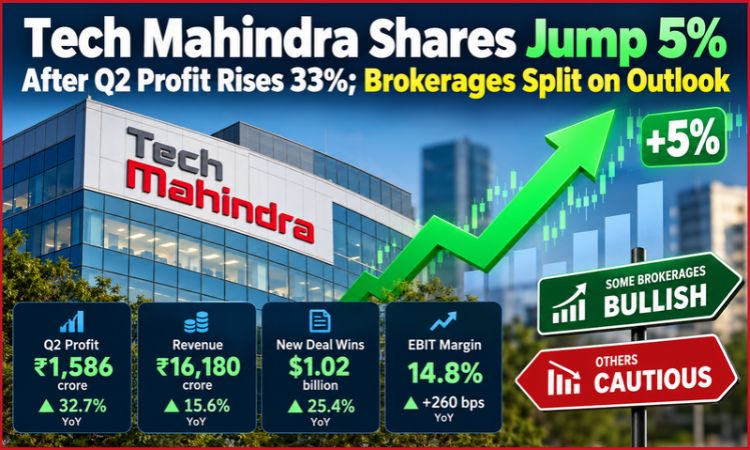
Tech Mahindra shares jumped as much as 5% on Friday after the IT services company reported another quarter of improving profit, stronger margins and more than $1 billion in new deal wins.
The stock touched ₹1,736 on the BSE after Tech Mahindra Q2 profit rose 32.7% year on year to ₹1,585.6 crore.
Revenue from operations increased 15.6% to ₹16,180.2 crore, while operating profit grew considerably faster.
Investors liked the numbers. Analysts were a little more divided.
Some brokerages see enough earnings and deal momentum to remain bullish, while others believe much of the improvement is already reflected in the stock price.
Revenue Growth Remained Healthy
Tech Mahindra reported quarterly revenue of ₹16,180 crore, up from ₹13,995 crore a year earlier.
Sequentially, revenue grew 3%.
In dollar terms, sales reached $1.69 billion, up 2% from the June quarter and 6.8% year on year.
Constant-currency growth was slightly stronger at 2.4% sequentially and 7.2% from a year earlier.
That puts Tech Mahindra revenue growth ahead of several large IT peers that are still struggling to generate meaningful sequential expansion.
It also shows that the company’s recovery is becoming less dependent on cost cutting alone.
Revenue is starting to contribute alongside margin improvement.
Profit Grew Faster Than Sales
The bigger change was visible lower down the income statement.
Profit after tax rose 32.7% year on year to ₹1,586 crore.
EBIT increased 40.5% to ₹2,387 crore.
That pushed the EBIT margin to 14.8%, around 40 basis points higher than the June quarter and roughly 260 basis points better than a year earlier.
The margin expansion is especially important because improving profitability has been one of Tech Mahindra’s main priorities during its turnaround.
Management has maintained a goal of delivering an average Tech Mahindra EBIT margin of 15% in FY27.
At 14.8%, the company is already operating close to that target.
Project Fortius Is Showing Up in the Numbers
Part of the margin recovery comes from Project Fortius, Tech Mahindra’s programme aimed at improving efficiency across the company.
That covers areas such as employee utilisation, subcontracting costs, organisational structure and the mix of work delivered from different locations.
AI is becoming part of the same discussion.
Management believes AI tools can help employees complete projects more efficiently and allow more contracts to move away from time-and-material billing towards fixed-price structures.
That shift matters.
In a traditional time-based contract, greater employee productivity can actually reduce billable hours.
In a fixed-price contract, finishing the same work more efficiently can instead improve the provider’s margin.
That makes AI productivity at Tech Mahindra potentially useful not only for customers but also for its own profitability.
New Deal Wins Stayed Above $1 Billion
Tech Mahindra recorded $1.02 billion in new deal wins during Q2.
That was 25.4% higher than a year earlier.
More importantly, it marked the fourth consecutive quarter in which new deal wins remained above the $1 billion level.
That consistency is one reason some brokerages are becoming more constructive about growth.
A large contract does not turn into revenue immediately. Deals normally ramp over several quarters as teams are assembled and systems are transitioned.
The company has two major telecom contracts won during the second half of FY26 that are still ramping.
Those contracts are expected to support growth through the current financial year.
Telecom Is Still Important, but Growth Needs to Broaden
Tech Mahindra has historically had far greater exposure to communications companies than most of its large Indian peers.
That can be an advantage when telecom spending is strong and a problem when operators pull budgets back.
Management is now trying to build a more balanced business.
Financial services, manufacturing, healthcare and other verticals are becoming increasingly important.
Brokerages are watching whether that diversification continues.
If Tech Mahindra growth depends primarily on two or three large telecom deals, investors may hesitate to apply a higher valuation.
If growth broadens across several industries, the recovery looks more durable.
Also Read : Wipro, Nestle India, Jio Financial Among 49 Firms Q2 Results
AI Revenue Disclosure Is Coming
Tech Mahindra is also preparing to give investors more detail about its artificial-intelligence business.
The company expects to begin disclosing AI revenue from the second half of FY27.
Its AI programme, TechM Helix, is moving from capability development into wider execution.
That disclosure will matter because investors are increasingly demanding numbers rather than general statements about AI demand.
TCS has already started highlighting annualised AI revenue, while Infosys has discussed how much of its business could eventually involve AI.
For Tech Mahindra, showing how much revenue is actually tied to AI services would allow investors to compare its progress more directly with peers.
Nuvama Sees More Room to Run
Nuvama is considerably more optimistic.
It maintained a Buy rating with a Tech Mahindra target price of ₹1,950.
The brokerage pointed to the run of $1 billion-plus deal wins and expects Tech Mahindra to outperform large-cap peers on growth during FY27.
Nuvama also expects margins to continue moving towards the company’s 15% goal.
Its earnings expectations are aggressive.
The brokerage forecasts a roughly 25% compound annual growth rate in earnings over the next two years.
If Tech Mahindra delivers that kind of growth, the current valuation becomes easier to justify.
Choice Keeps an Add Rating
Choice Institutional Equities sits somewhere between the two positions.
It maintained an Add rating with a target of ₹1,775.
The brokerage also sees scope for continued productivity gains through AI tools, workforce optimisation and other operating efficiencies.
It expects the communications pipeline to remain strong and sees banking and financial services returning to faster growth.
Weakness in Europe’s automotive market remains a risk, but Choice does not currently view it as large enough to derail the broader recovery.
The different recommendations show why the Tech Mahindra share price debate is not about whether Q2 was good.
It was.
The debate is about how much future improvement investors should pay for today.
The Next Phase Is About Growth, Not Just Repair
Tech Mahindra has already made substantial progress on the profitability side.
Margins have expanded. Deal wins remain healthy. Profit is growing much faster than revenue, and the company is approaching its FY27 margin target.
The next challenge is harder.
Management now needs to show that revenue growth can remain strong after the current large contracts finish ramping.
That means winning more work outside telecom, turning AI capability into measurable revenue and maintaining margins without relying only on cost reductions.
Friday’s 5% rally shows investors were encouraged by the September quarter.
Whether the Tech Mahindra stock rally continues will depend on whether Q2 turns out to be another step in a sustained growth cycle rather than simply a strong quarter inside a turnaround.