Wipro’s September-quarter numbers came with two very different signals. Revenue edged ahead of expectations and margins improved, but profit slipped and the company’s large-deal pipeline weakened sharply from the previous quarter.
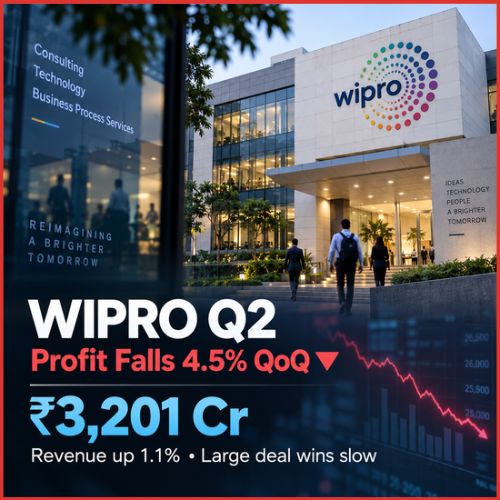
The IT services company reported Wipro Q2 net profit of ₹3,200.6 crore, down 4.5% sequentially. Revenue from operations, meanwhile, rose 1.1% quarter on quarter to ₹24,752.7 crore.
Compared with a year earlier, gross revenue was up 9.1%, while net income declined about 1.9%.
The quarter was not a clear miss. It was not a strong growth quarter either. Wipro is still operating in a market where clients are spending carefully, while much of the new technology budget is moving towards AI-led projects rather than traditional discretionary work.
IT Services Revenue Was Almost Flat
Wipro’s core IT services business generated $2.61 billion during the quarter.
Reported dollar revenue slipped 0.1% sequentially. In constant-currency terms, which removes the effect of exchange-rate movements, revenue was flat from the June quarter and only 0.6% higher year on year.
That tells the underlying story more clearly than the 9.1% increase in rupee revenue.
Currency movements helped the reported top line, but Wipro IT services revenue itself barely moved during the quarter.
For investors looking for evidence of a broader recovery in technology spending, that is likely to be one of the more important details.
Demand has stabilised in parts of the market, but the acceleration remains uneven.
Margins Improved to 16.5%
Profitability was better.
Wipro’s IT services operating margin rose to 16.5%, up 50 basis points from 16% in the June quarter.
That improvement came despite the company continuing to invest in employees, consulting capabilities and artificial intelligence.
Margins are particularly important for Wipro because the company has been trying to improve execution while returning to stronger growth.
When revenue is barely moving, cost control becomes even more important.
The higher Wipro operating margin suggests the company found enough efficiencies during Q2 to absorb some of the pressure from slower business growth.
Still, margins were 20 basis points lower than a year earlier, so the improvement is more convincing sequentially than annually.
Large Deal Bookings Fell Sharply
The bigger concern came from bookings.
Total contract bookings stood at $2.6 billion, down 22.9% sequentially in constant currency.
Large-deal bookings dropped much faster, falling 58.6% from the previous quarter to $674 million.
For comparison, large deals had reached about $1.63 billion in Q1.
That does not mean Wipro suddenly lost all large-contract opportunities. Deal awards can move around considerably from one quarter to another, especially when clients delay final decisions.
Even so, the Wipro large deal bookings figure is difficult to ignore because large contracts provide an important source of future revenue visibility.
Management will need the pipeline to convert more strongly over the coming quarters if Wipro wants growth to move meaningfully higher.
Q3 Guidance Remains Cautious
The company’s outlook for the December quarter is still subdued.
Wipro expects IT services revenue of $2.57 billion to $2.63 billion in Q3.
In constant-currency terms, that translates to sequential growth ranging from a 1.5% decline to a 0.5% increase.
That is a fairly wide range, but neither end points to a major acceleration.
The Wipro Q3 guidance therefore suggests management is not expecting demand conditions to change dramatically over the next three months.
A few large deals could improve the picture later, but Wipro is not building that possibility aggressively into its immediate guidance.
This cautious approach is consistent with what other large Indian IT companies have been saying: demand is improving in selected areas, but discretionary spending has not fully returned.
Cash Generation Was Much Stronger
One area where the quarter looked particularly healthy was cash flow.
Operating cash flow rose 61.3% sequentially to around ₹5,305 crore.
That represented 165.8% of net income.
Free cash flow came in at approximately ₹4,888 crore.
Strong cash conversion matters because it gives Wipro room to fund investments, acquisitions and shareholder returns without relying heavily on debt.
It also provides some reassurance when accounting profit itself declines.
The company may have earned less than in the June quarter, but a significantly larger amount of cash moved through the business.
Employee Count Fell by More Than 6,700
Wipro ended the quarter with 236,328 employees.
That was 6,716 fewer than the 243,044 people on its rolls at the end of Q1.
Voluntary attrition was largely stable at 13.8%, compared with 13.9% in the previous quarter.
The headcount reduction is worth watching because AI and automation are changing the relationship between employee numbers and revenue across the IT industry.
Technology companies increasingly want to generate more revenue without increasing headcount at the same pace.
For Wipro, productivity improvements can support margins. The other side is that sustained growth will still require the right mix of engineering, consulting and AI skills.
Wipro Shares Still Found Buyers
Despite the profit decline and weaker bookings, investors reacted positively to the quarter.
Wipro shares rose after the results, with the stock gaining nearly 4% at one point on Friday.
The market appeared to focus on the modest revenue beat, improved margins and management’s confidence that delayed deals could eventually close.
The stock has still had a difficult 2026 and remains well below levels seen earlier in the year.
That makes expectations important.
When a stock has already fallen substantially, results do not necessarily need to be spectacular to trigger a rally. Sometimes they only need to be less weak than investors feared.
The Revenue Recovery Still Needs More Evidence
The September quarter leaves Wipro Q2 results somewhere in the middle.
Revenue beat expectations slightly. Margins improved. Cash generation was strong, and management continues to find AI-related transformation work.
But the main growth engine has not yet picked up much speed.
Constant-currency IT services revenue was flat. Large deal bookings dropped sharply, and Q3 guidance points to another quarter where growth could remain close to zero.
That makes the next few months important.
If delayed deals finally convert and AI-led projects begin adding more revenue, Q2 may look like a stabilisation quarter before growth improves.
If bookings remain weak, the margin improvement alone will not be enough to change the broader story.