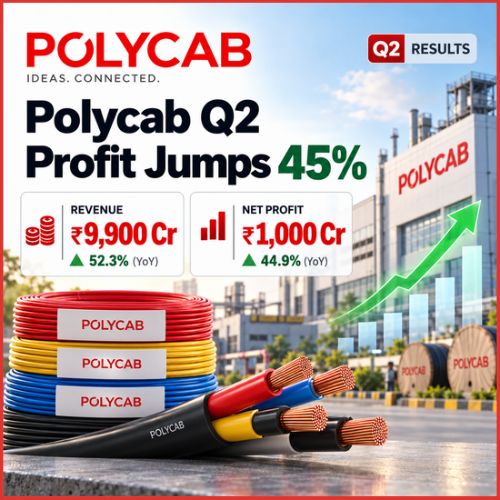
Polycab India has delivered a much stronger September quarter than the market was expecting, with revenue approaching ₹10,000 crore and net profit reaching ₹1,000 crore for the first time in the quarter.
The wires and cables maker reported Polycab Q2 revenue of ₹9,900 crore, up 52.3% from ₹6,500 crore in the same period last year. Consolidated net profit rose nearly 45% to ₹1,000 crore from ₹690 crore.
Both numbers comfortably beat analyst estimates.
The strong top-line growth comes at a time when India’s cables industry is seeing healthy demand from infrastructure, real estate, power projects and newer areas such as data centres and renewable energy. The tougher part of the quarter was profitability at the operating-margin level, where higher input costs continued to leave their mark.
Revenue Beat Estimates by More Than ₹1,000 Crore
The scale of the revenue beat was hard to miss.
Analysts had expected Polycab to report roughly ₹8,889 crore in consolidated revenue. The actual number came in at ₹9,900 crore, more than 11% ahead of that estimate.
Year on year, the increase was ₹3,400 crore.
That is a considerable jump for a company already operating at significant scale.
It also continues the strong start Polycab made to FY27. In the June quarter, revenue had reached ₹8,210 crore, up 39% year on year.
Compared with that quarter, Polycab India revenue rose another 20% or so in Q2.
The momentum suggests demand has remained strong even as higher metal prices have forced cable makers to adjust product prices.
Profit Crosses ₹1,000 Crore
The bottom line was another clear positive.
Polycab’s consolidated net profit increased from ₹690 crore a year ago to ₹1,000 crore in Q2, representing growth of about 44.9%.
Consensus was closer to ₹820 crore.
That means the company beat profit estimates by roughly 22%.
Sequentially, profit also improved sharply from the June quarter, when Polycab had reported around ₹797 crore.
For investors, the combination matters. Rapid revenue growth is useful, but it becomes far more meaningful when enough of it reaches the bottom line.
The latest Polycab Q2 results 2026 managed to deliver both.
EBITDA Reaches ₹1,420 Crore
Operating profit stood at ₹1,420 crore during the quarter.
That compares with ₹1,020 crore in the same period last year and was well above the market estimate of approximately ₹1,221 crore.
So EBITDA grew by around 39%.
The EBITDA margin came in at 14.37%.
That figure deserves a little more attention because it tells a more nuanced story than the revenue and profit numbers alone.
A year ago, Polycab had reported a margin of 15.76%.
So despite the large increase in sales and operating profit, the margin narrowed by 139 basis points year on year.
Still, analysts had expected it to fall further to roughly 13.7%.
In other words, Polycab EBITDA margin weakened from last year’s unusually strong level but held up better than the Street had anticipated.
Copper Prices Remain a Complication
Raw materials are an unavoidable part of the story for any cables manufacturer.
Copper and aluminium account for a substantial portion of production costs, which means sharp movements in metal prices can quickly affect margins.
Copper prices have risen significantly over the past year, forcing cable manufacturers to increase selling prices.
So far, the industry has largely been able to pass those higher costs on to customers without creating a major collapse in demand.
That has helped revenue growth.
But price-led growth does not always produce the same operating leverage as volume-led expansion. If raw-material costs rise quickly, manufacturers can sell more in rupee terms while still seeing pressure on percentage margins.
That is one reason the margin picture in the Polycab earnings looks less spectacular than the revenue number.
Demand From Infrastructure Remains Strong
The other side of the equation is demand, and that remains favourable.
India continues to spend heavily on power networks, transport infrastructure, commercial construction and industrial capacity.
Each of those areas requires wires and cables.
The spread of renewable-energy projects adds another source of demand, as does the expansion of data centres, which require large amounts of electrical infrastructure.
Residential and commercial real estate remain important as well.
This gives established manufacturers such as Polycab exposure to several investment cycles rather than one narrow end market.
That broad demand base is one reason the company has been able to sustain strong growth even while commodity prices remain volatile.
Wires and Cables Remain the Core Business
Polycab is increasingly present across fast-moving electrical goods, or FMEG, but wires and cables still make up the overwhelming majority of its business.
In Q1 FY27, the segment contributed more than 87% of consolidated segment revenue and grew nearly 38% year on year.
FMEG grew even faster during that quarter, rising more than 67%.
Products in that business include fans, switches, lighting, switchgear and water heaters.
The smaller consumer business gives Polycab another growth avenue beyond large cable projects, although wires and cables remain the main earnings engine.
The company’s ability to grow both sides will matter as competition in the electrical-products industry becomes more intense.
Expectations Were Already High Before the Result
Investors had entered Q2 expecting another good quarter.
Brokerage estimates ahead of the earnings announcement pointed to sales growth of around 18-20% for major cable manufacturers, supported by strong demand and product price increases.
Polycab ended up comfortably exceeding those expectations.
That makes the latest numbers particularly notable because the comparison base was hardly weak.
The company had already reported strong growth through FY26 and followed that with record first-quarter revenue in FY27.
Continuing to grow at more than 50% year on year from that base sets a considerably higher benchmark for coming quarters.
Margin Sustainability Becomes the Next Question
After a result this strong, the most obvious question is what happens next.
Revenue and profit have beaten estimates by wide margins. The demand environment remains supportive.
Margins are where investors may spend more time.
If copper and aluminium prices continue rising, Polycab will need to keep passing those costs on without affecting volumes. Competition in FMEG could create additional pressure as well.
The company’s management commentary after the results should therefore be important, particularly around commodity prices, demand visibility and the outlook for the second half of FY27.
For now, though, the quarter itself gives investors little to complain about.
Polycab net profit has crossed ₹1,000 crore, revenue is nearing the five-digit crore mark in a single quarter, and all three headline measures of sales, EBITDA, and profit, came in above market expectations.
The margin may have slipped from last year’s high base, but even there, Polycab did better than analysts had pencilled in.
Source
Polycab Posts Q2 Revenue Of ₹9,900 Crore And Net Profit Of ₹1,000 Crore